
Is Your Mortgage Pre-Approval a Guarantee? Your Finance Loan Guide
I remember the exact moment I got my first pre-approval letter—I felt like I had already won the lottery and started planning where to put my furniture. I was so convinced that the house was mine that I nearly put down a deposit on a new sofa before the bank had even finished reviewing my taxes. Little did I know, that little piece of paper wasn't the golden ticket I thought it was, and I almost lost my dream home because of it.
You found the perfect house. The kitchen has the exact quartz countertops you wanted, the backyard gets warm afternoon sun, and the neighborhood feels safe.
Even better, you hold a crisp letter from a bank stating you are pre-approved. You make an offer, the seller accepts, and you start packing your boxes.
Looking back, my biggest mistake was thinking that "pre-approved" meant I could stop being careful with my spending. I actually bought a new laptop on a store credit card during escrow, not realizing how much a tiny monthly payment could mess up my debt-to-income ratio. If I could go back, I would have locked my credit cards in a safe the second my offer was accepted and stayed completely quiet with my bank accounts.
Then, two weeks before closing, your loan officer calls with bad news: your mortgage loan application hit a wall.
It is one of the most painful surprises in real estate. Many buyers believe a pre-approval letter is a signed promise that the bank will hand over the money.
In reality, it is not a promise at all.
Welcome to our complete finance loan guide, designed to pull back the curtain on the lending process. In this finance loan guide, we will explain what pre-approval actually means, why lenders change their minds, and how you can protect your transaction from start to finish.
If you want to keep your home purchase on track, this finance loan guide will show you how to navigate every bump in the road.
What Pre-Approval Really Means in a Finance Loan Guide
When shopping for a home, you will hear terms like pre-qualification, pre-approval, and underwriting. Lenders sometimes use them loosely, which causes heavy confusion for buyers.
According to standard lending practices outlined in any trusted finance loan guide, pre-qualification is just an informal first look. You tell a lender what you make, what you owe, and what you have saved.
The lender takes your word for it without checking your documents. They give you a rough estimate of what you might be able to borrow.
Pre-approval goes one step further. The lender pulls your credit report, looks at your recent W-2 forms, checks pay stubs, and reviews bank statements.
Because they verified actual paperwork, they hand you a formal pre-approval letter. This letter tells real estate agents and sellers that you have the financial backing to make an offer.
However, as this finance loan guide must stress, a pre-approval letter is still an estimate. It simply means: "Based on what we see right now, you qualify for this mortgage loan—assuming nothing changes about you or the property."
The table below breaks down the key stages covered in our finance loan guide:
As shown in this finance loan guide, your journey is not finished when you receive that initial pre-approval slip. You have merely cleared the first hurdle of securing a mortgage loan.
Why a Mortgage Loan Pre-Approval Is Never a 100% Guarantee
Why won't a lender make a binding promise during pre-approval? The answer comes down to risk and timing.
A pre-approval is what the industry calls a conditional approval. It comes attached to a long list of requirements that you and the property must meet before any cash moves.
When an underwriter evaluates your file, they work for an institution that must protect its capital. They cannot issue an ironclad commitment until every single puzzle piece is in place.
Most pre-approval letters include fine print at the bottom. If you read that fine print through the lens of this finance loan guide, you will see phrases like:
- "Subject to satisfactory property appraisal."
- "Contingent upon no material changes in credit score or employment status."
- "Verification of acceptable property title and hazard insurance."
These clauses mean the bank reserves the right to walk away at any second. If interest rates spike, your debt goes up, or the home fails an inspection, the deal can fall apart.
Our finance loan guide exists to help you understand that a pre-approval letter is a snapshot of a single day. If the picture changes tomorrow, the lender's decision can change right along with it.
The Hidden Conditions Every Finance Loan Guide Warns You About
Every conditional approval includes specific requirements called "loan conditions." These conditions are standard hurdles every borrower must jump over.
Here are three primary conditions that this finance loan guide urges you to watch closely:
1. The Property Appraisal Condition
The bank will only lend money based on the fair market value of the home, not the price you agreed to pay. If you offer $400,000, but the independent appraiser says the home is only worth $380,000, an appraisal gap occurs. The bank will not write a mortgage loan for the extra $20,000 without additional cash from you.
2. Clear Title and Property Search
A lender will not fund your purchase if there are legal claims against the house. Liens from unpaid contractors, back taxes, or probate disputes can stall the transaction. As detailed in this finance loan guide, title issues have killed countless approvals that looked solid on paper.
3. Final Verification of Employment (VOE)
Underwriters will call your employer again roughly 24 to 48 hours before closing. They want to confirm you have not been laid off, quit, or had your hours cut. If your job status changes, your mortgage loan approval vanishes instantly.
5 Costly Mistakes That Can Kill Your Mortgage Loan at the Finish Line
Watch this breakdown to see exactly how small financial moves during escrow can accidentally ruin your chances of closing on your new home.
Most buyers assume that once they have a pre-approval letter, they are free to live normally. That assumption is dangerous.
The weeks between your offer acceptance and closing day require complete financial discipline. To help you steer clear of pitfalls, our finance loan guide highlights the five most common errors buyers make.
MORTGAGE DANGER ZONE (Between Contract & Closing)
1. Opening New Lines of Credit
Do not finance a new car, a riding lawnmower, or living room furniture before you get the keys. Every new credit account adds monthly obligations, which raises your debt-to-income (DTI) ratio.
Even a hard credit inquiry can drop your score by several points. If your score hovers right on the edge of qualification, that small drop can invalidate your pre-approved mortgage loan.
2. Changing or Leaving Your Job
Lenders love stability. They want to see at least two consistent years in the same line of work.
If you switch from a salaried role to an independent contractor position, underwriters will hit the brakes. 1099 contractors usually need two years of tax returns to prove reliable earnings.
Even taking a higher-paying job in a brand-new field can trigger delays. As this finance loan guide always recommends, stay put at your current job until all loan documents are signed.
3. Depositing Untraceable Cash
You cannot deposit a stack of cash from an envelope into your bank account during escrow. Anti-money laundering rules require lenders to verify the exact paper trail of every single dollar used for down payments and closing fees.
Unverified deposits will be excluded from your available funds. In worse cases, they can prompt underwriters to audit your entire account.
4. Missing Bill Payments
This point may seem obvious, but moving is stressful and bills can slip through the cracks. A single 30-day late payment on a credit card or auto loan can drop your credit score by 50 to 100 points.
If that happens mid-escrow, your mortgage loan terms will worsen, or the loan will be denied outright.
5. Co-Signing for Family or Friends
Helping a family member buy their first car while you are buying a home is a catastrophic error. When you co-sign, you become 100% legally responsible for that debt in the underwriter's eyes.
That monthly payment is added directly into your debt calculations. As this finance loan guide reminds buyers, protect your own borrowing profile first.
Real-Life Case Study: How Sarah Lost Her Dream Home
To see how fragile pre-approval can be, let us look at a real scenario we observed while developing this finance loan guide.
Sarah was a graphic designer earning $78,000 a year. She worked hard, kept her credit score at 715, and saved $35,000 for a down payment.
She worked with a local broker who issued a strong pre-approval letter for a $320,000 mortgage loan. Her debt-to-income ratio sat at a safe 38%.
Sarah found a house she loved, made an offer, and entered a 30-day closing period.
Three weeks in, the seller's agent confirmed the appraisal came back right on value. The title was clean, and Sarah was thrilled.
Assuming the hard part was behind her, Sarah took advantage of a holiday sale at a local furniture store. She bought a washer, a dryer, and a sectional couch for $4,500 using a store credit card with "zero percent interest for 12 months."
She thought: "I don't have to pay interest, so it won't count against me."
She was mistaken.
Two days before closing, the lender pulled a routine "soft credit refresh." The new furniture account popped up immediately.
Even though the promotional interest rate was zero, the lender was required to calculate a minimum monthly payment for the balance. That extra $130 monthly payment pushed Sarah's DTI ratio past the lender's strict 43% cap.
Her mortgage loan was denied 48 hours before closing. She lost her earnest money deposit of $5,000 and the house went back on the market.
This story is a sobering lesson. Follow this finance loan guide: keep your credit cards locked in a drawer until the home purchase is legally recorded.
The Property Factor: When the House Ruins Your Mortgage Loan
Sometimes, your personal finances remain pristine, but the deal still falls apart. That happens because a mortgage loan involves two parties: you and the property.
The house serves as collateral for the bank's investment. If you stop paying, the bank needs to know they can sell the home to recover their funds.
If the home has major flaws, the lender will refuse to finance it, regardless of your 800 credit score.
Common Property Red Flags
- Appraisal Shortfalls: If buyers overbid during a bidding war, the home might not appraise for the offer price. Unless the buyer brings extra cash or the seller drops the price, the loan dies.
- Health and Safety Violations: Government-backed loans like FHA and VA have strict property standards. Peeling lead-based paint, missing handrails, leaking roofs, or broken HVAC systems must be repaired before funding.
- Homeowners Association (HOA) Problems: If you buy a condo or townhome, the bank investigates the HOA's financial stability. If too many owners are delinquent on dues, or if the HOA is involved in structural lawsuits, lenders will blacklist the entire complex.
- Water and Pest Inspections: Termite damage or contaminated well water can stop an underwriter cold until certified treatments are complete.
This finance loan guide always suggests adding a loan contingency and an appraisal contingency to your purchase offer. These contingencies give you an exit door to recover your deposit if the house fails the lender's evaluation.
Step-by-Step Action Plan: How to Protect Your Approval to the Closing Table
Now that you know what can go wrong, let us focus on what you can do right. Protecting your mortgage loan requires a steady, organized approach.
Use this step-by-step checklist from our finance loan guide to keep your pre-approval safe through the entire closing process.
Step 1: Seek an Underwriter-Reviewed Pre-Approval
Ask your lender if an actual underwriter can review your file before you find a house. Some lenders call this a "verified pre-approval" or "credit-underwritten pre-approval."
Because an underwriter examines your taxes and income up front, this letter carries far more weight than a basic pre-approval generated by a sales officer.
Step 2: Document Every Dollar
If a family member gives you money toward your down payment, use a formal gift letter. The letter must state that the money is a gift, not a loan that must be paid back.
Never transfer funds between personal accounts without saving copies of the transfer receipts. Our finance loan guide emphasizes clean paper trails above all else.
Step 3: Put Your Finances in Freezing Mode
From the moment you apply for a mortgage loan until the deed is signed:
- Do not apply for any new credit cards.
- Do not finance vehicles, electronics, or furniture.
- Do not pay off old collections without consulting your loan officer first.
- Keep paying all existing debts on time, every time.
Step 4: Keep an Open Line with Your Loan Officer
If you expect changes at work—such as an adjusted commission structure, a planned transfer, or an extended leave of absence—talk to your lender immediately.
Surprises will derail your loan. Giving your lender early notice lets them build a workaround before the file reaches the final audit.
Step 5: Wait for the Official "Clear to Close"
Do not hire movers or schedule utility transfers based solely on a conditional pre-approval. Wait until your loan officer tells you that you have achieved Clear to Close (CTC) status.
Clear to Close means the underwriter has reviewed every condition, the appraisal is approved, and the lender is preparing the final wire transfer.
Essential Finance Loan Guide Checklist for Homebuyers
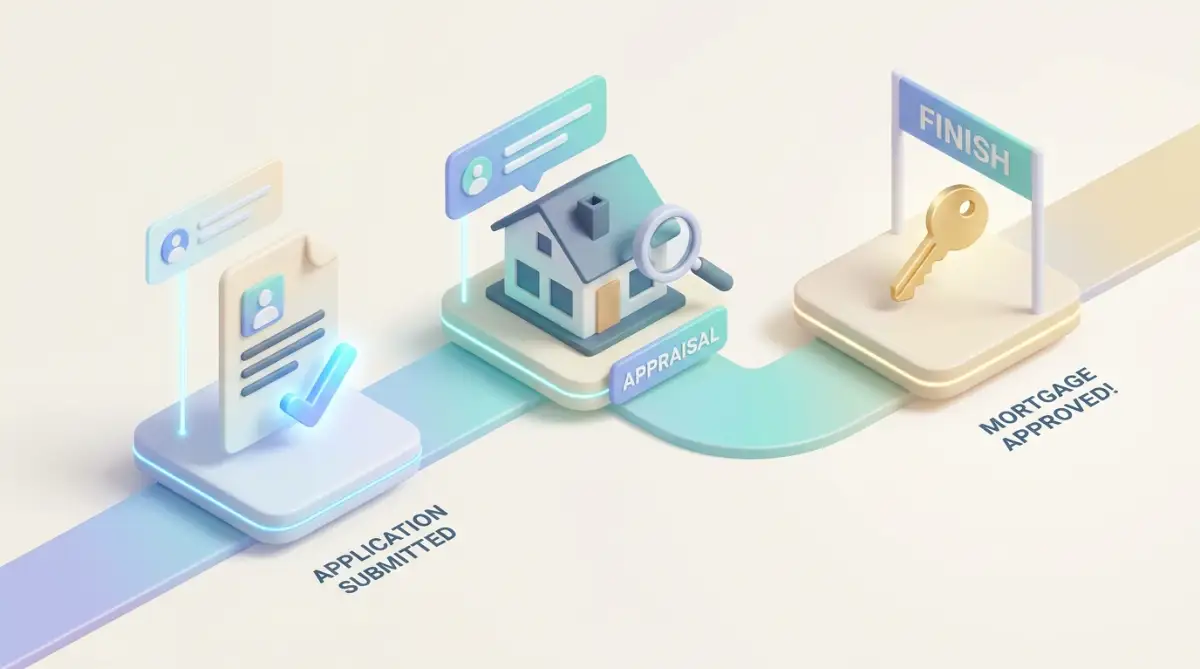
To keep these rules handy, use this quick-reference table directly from our finance loan guide. Review it before making any financial move during your home search.
Following the dos and don'ts in this finance loan guide prevents self-inflicted mistakes that could jeopardize your mortgage loan.
What to Do If Your Mortgage Loan Gets Denied After Pre-Approval
Even when you follow every rule in this finance loan guide, unexpected roadblocks can occur. An unexpected tax lien might surface, or an appraisal might come back dangerously low.
If your lender issues an unexpected denial, take a breath. A denial feels like a heavy blow, but it does not mean your path to homeownership is closed forever.
Follow these recovery steps:
1. Demand the Adverse Action Notice
Federal law requires lenders to send you an Adverse Action Notice explaining exactly why your loan was declined. Read this document carefully.
It will pinpoint whether the problem was your credit score, insufficient reserves, high debt ratios, or the property itself.
2. Check for Simple Errors
Mortgage processing teams handle hundreds of pages of documentation. Clerical mistakes happen.
Did an underwriter miss an asset account? Did they mistakenly count a student loan that is in authorized deferment?
Review the numbers with your loan officer to ensure the denial was not based on a math mistake.
3. Consider an Alternative Loan Program
If you were rejected for a Conventional mortgage loan, an FHA loan might fit your scenario better. FHA loans permit higher debt ratios and lower credit scores.
If you are a military veteran, a VA loan offers flexible underwriting terms. Use this finance loan guide to explore alternative financing pathways.
4. Renegotiate with the Seller
If the home failed its appraisal, the ball is in the seller's court. Show the seller the appraisal report.
Remind them that any other buyer using a mortgage loan will encounter the exact same problem. Many sellers will drop their asking price rather than restart the listing process from scratch.
5. Rebuild and Reapply
If the issue stems from credit or excessive debt, spend three to six months fixing the root cause. Pay down revolving credit cards to lower your utilization rate.
Save an extra cushion of cash reserves to make your file look bulletproof on your next application.
Frequently Asked Questions (FAQ)
How long does a mortgage loan pre-approval letter remain valid?
Most pre-approval letters last between 60 and 90 days. Lenders use this timeframe because credit reports, interest rates, and asset balances change quickly. If your letter expires before you find a home, your lender will need updated pay stubs and a fresh credit check to renew it.
Can a lender cancel a mortgage loan after issuing a pre-approval?
Yes, a lender can revoke an approval at any point up to the day of funding. Cancellations usually occur due to job changes, new debts, credit score drops, or problems discovered during the property appraisal and title search phases of underwriting.
What is the difference between pre-approval and Clear to Close?
A pre-approval is an initial estimate based on preliminary reviews of your finances. Clear to Close means the underwriter has verified every condition, approved the property's appraisal and title, and authorized the final release of funds. Clear to Close is the true confirmation of your loan.
Will applying for a mortgage pre-approval hurt my credit score?
A pre-approval requires a hard credit pull, which typically dings your score by two to five points. However, credit bureaus treat multiple mortgage inquiries within a 14 to 45-day window as a single event. This shopping window allows you to compare lender quotes without compounding credit damage.
How much cash should I keep in reserves during the mortgage process?
Lenders prefer to see two to six months' worth of total housing payments (principal, interest, taxes, and insurance) left in your accounts after paying your down payment and closing costs. These reserves prove that you can handle unexpected financial emergencies without defaulting on your loan.
Final Thoughts: Taking Control of Your Home Purchase
Walking into the housing market with a pre-approval letter gives you confidence, and it should. It proves that you have solid credit, steady income, and the ambition to invest in your future.
Just remember that a pre-approval letter is an invitation to dance, not the final song.
Treat your finances with extreme care while shopping for a home. Treat every bank statement, pay stub, and credit card swipe as a piece of evidence that an underwriter will scrutinize.
Don't let the fear of these rules stop you from chasing your goal of homeownership. When you treat your finances with respect and stay patient through the process, the keys to your new front door will be in your hands before you know it. Start gathering your documents today, stay disciplined, and stay excited—you are closer to owning your home than you think.
By applying the lessons outlined in this finance loan guide, you remove guesswork from the equation. You protect your earnest money, preserve your peace of mind, and ensure that your mortgage loan moves across the finish line without unexpected hurdles.
Whenever you feel uncertain about a financial decision during the escrow process, consult this finance loan guide and speak directly with your loan team.
Ready to make your next move? Gather your documents, partner with an underwriter-verified lender, and step forward toward closing day with total confidence.

