
The Quiet Panic of an Overdue Second Mortgage
If your home equity payment deadline slipped past you yesterday, take a slow breath. You are not going to lose your house tomorrow morning. Missing a second mortgage bill feels terrifying because your actual roof is on the line, but banks do not jump straight to foreclosure over a single late slip. You have built-in legal cushions, clear deadlines, and direct workout options that can protect your equity—as long as you take charge before the 30-day mark hits."
You wake up in the middle of the night, and your chest feels tight. That familiar paper envelope or electronic alert is sitting on your kitchen counter, and you know the payment deadline has quietly passed. A few years back, I found myself in this exact spot when an unexpected medical bill drained my checking account right before my second mortgage was due. I remember sitting on the edge of my bed at 3:00 AM, staring at the bank alert on my phone with a knot in my stomach so tight I could barely breathe. I convinced myself that my family was going to lose our home just because of one bad month. That paralyzing fear was real, but facing it head-on taught me that lenders actually have rules that protect you if you speak up early.
Simple routines like buying groceries or filling up your car start carrying a cloud of guilt. You find yourself second-guessing every tiny expense because your mind is constantly calculating the money you do not have. The silence that follows a missed due date is often the hardest part to bear. You wonder if your phone will ring today, or if a formal warning letter will show up in tomorrow's mail.
Why Most Borrowers Get Trapped by Bad Information
┌──────────────────────────────────────────────────────────────────────────┐
│ 📌 Quick Action Plan: What You Need to Know Right Now │
├──────────────────────────────────────────────────────────────────────────┤
│ • Day 1 to 15 Grace Period: No credit bureau reporting happens, and your │
│ credit score remains completely safe during this window. │
│ • Ask for "Homeowner Retention": Never discuss long-term repayment terms │
│ with standard reps; demand the department authorized to waive fees. │
│ • Your Equity is Leverage: If your home has market value above what you │
│ owe, your lender would rather modify the terms than file foreclosure. │
│ • Never Skip Letters: Read every legal notice immediately; the 30-day │
│ "Right to Cure" letter holds the key to formal forbearance relief. │
└──────────────────────────────────────────────────────────────────────────┘
When financial stress hits, people turn to search engines and internet forums, but the advice out there is often dangerously flawed. Most people freeze simply because they do not know which rules apply to their exact situation.
- Treating second mortgages like unsecured personal loans: Many borrowers wrongly assume a home equity loan works like an unsecured credit line, thinking the bank will just send angry letters. In truth, your home acts as the physical collateral securing every single dollar.
- Believing lenders want to take your house instantly: Internet horror stories make it seem like lenders send eviction notices after one late payment. That fear causes borrowers to hide their heads in the sand instead of using established legal protections.
- Listening to outdated word-of-mouth advice: Friends and family often give tips based on standard first mortgages, completely missing how junior liens work during a default.
- Assuming silence buys you extra time: Borrowers often think that if the lender has not called, the missed payment went unnoticed. In reality, automated bank systems are already counting the days and adding penalty charges behind the scenes.
How Missed Payments Drain Your Mental Peace and Confidence
Financial strain does not just damage your bank account; it takes a heavy toll on your emotional health and your sense of stability.
- The burden of constant secrecy: You might feel ashamed to talk to your partner, your children, or your friends about what is happening. Keeping that secret turns a temporary cash problem into an exhausting daily performance.
- A feeling of lost control over your sanctuary: Your home is supposed to be your safe harbor from the world. The moment you fall behind on a loan tied to that roof, home stops feeling peaceful.
- Analysis paralysis that blocks simple actions: When stress spikes, your brain switches to basic survival mode. Opening simple bank mail begins to feel like touching a hot stove, so you delay opening letters that actually contain relief options.
- Erosion of personal self-worth: It is easy to confuse a temporary cash shortage with personal failure. You forget that unexpected medical bills, job shifts, and sudden repair costs happen to millions of responsible families every single week.
The True Anatomy of a Second Lien Default
To understand what you are facing, you have to peel back the paperwork. A home equity loan is what the banking industry calls a second mortgage or a junior lien.
When you bought your home, your primary mortgage holder took the first spot in line. Your home equity lender sits right behind them, holding a legal claim against the exact same title.
Because they sit in second position, their risk is much higher if things go wrong. If a foreclosure sale occurs, the first mortgage lender gets paid off down to the very last penny before your home equity lender sees a single cent.
| Second Lien Myth | What Actually Happens | How It Helps You |
| :--- | :--- | :--- |
| Myth: "The bank will foreclose on day 31." | Foreclosure is a last-resort legal process that takes 4 to 12 months. | You have a realistic window to arrange a payment plan. |
| Myth: "The second lender keeps all the money." | First mortgage holders get paid 100% of their balance first. | A junior lender often prefers negotiating over expensive legal battles. |
| Myth: "Hiding out delays bank actions." | Computer systems add fees and report default automatically. | Direct early contact freezes collections and unlocks hardship relief. |
This financial ranking changes how the lender responds to you. They are not mindless enemies, but they are focused on protecting their capital before your equity vanishes.
When you miss a payment, a strict legal clock begins ticking inside their servicing software. The consequences unfold in clear, predictable stages, and knowing the timeline gives you your power back.
You do not have to live in fear of the unknown. Let us break down the exact sequence of events and examine the first real moves you can make starting today.
Taking Control: The First Three Moves to Protect Your Home
Watch this short walkthrough to see the exact moves you must make the moment your second mortgage payment is past due. Spend two minutes watching this step-by-step breakdown, then follow our detailed checklist below to protect your home.
When you are dealing with a missed home equity payment, speed and clear thinking are your best allies. You do not need complicated financial formulas to begin fixing this.
You only need an orderly plan that addresses the lender's rules step by step. Here are the first three practical moves you must take to stop collection actions and safeguard your home.
Step 1: Use the Grace Period and Open the Line of Communication
Almost every home equity loan comes with a built-in safety cushion known as the grace period. In most standard loan contracts, this window lasts between 10 and 15 days past your official due date.
Timeline Status Impact & Safety Payment Due Date Due Date No penalty yet 10 to 15-Day Grace Period
If your payment is due on the first day of the month, your servicer usually will not charge a penalty until the sixteenth. Even better, credit reporting bureaus do not consider a payment delinquent until it is a full 30 days past due. That means if you are only five or ten days late, your credit score has not suffered any permanent damage yet. You have a golden opportunity to resolve the issue before it touches your public record. Call your loan servicer before that 15-day mark expires. Do not wait for their automated collections unit to dial your number first.
When you pick up the phone, ask to speak directly with the homeowner retention department rather than a standard customer service agent. Retention agents have the direct authority to waive one-time late fees and pause collection activities. Be ready with a short, honest summary of what happened. Tell them: "I experienced an unexpected car repair this month, which caused me to fall behind, but I am committed to keeping this account current." Lenders document every incoming call in their system. A logged call showing proactive intent immediately marks your account as low risk, buying you room to work out a solution.
"Hi, my account number is [Your Account #]. I had an unexpected emergency expense this month and fell slightly behind on my due date. I want to keep this loan in good standing. Could you please connect me with the homeowner retention department so we can discuss a one-time late fee waiver and set an agreed payment catch-up date before Day 30?"
(Tip: Always jot down the date, time, and the representative's employee ID on your notepad before you hang up.)
When I finally got the courage to pick up the phone, my biggest early mistake was rambling about my anxiety to the frontline customer service rep instead of asking for the homeowner retention department. Once I reached a retention specialist, the conversation shifted completely. The agent waived my late fee right away, logged my payment date, and gave me back two weeks of uninterrupted peace of mind.
Step 2: Audit Your Lien Hierarchy and Uncover Your True Cash Flow
Once you have spoken to your servicer, sit down with a plain notepad and look at your entire debt picture. You need to know exactly who holds legal claims against your property. Pull out your latest statements for both your first mortgage and your home equity loan. Write down three specific numbers for each account:
- The exact current principal balance.
- The exact monthly minimum payment.
- The exact interest rate and payment due date.
Next, look at the estimated market value of your house using recent neighborhood sales. Subtract your primary mortgage balance and your home equity balance from that estimated value.
The number left over is your remaining equity cushion. This number is your shield.
If your home has substantial equity, your home equity lender has a strong incentive to work with you rather than initiate a costly legal dispute. Foreclosures cost lenders thousands of dollars in administrative and legal fees. Now, look at your monthly household expenses for the past thirty days. Separate your spending into basic survival needs and non-essential items.
Your survival needs are straightforward: shelter, basic food, necessary utilities, and reliable transportation to work. Everything else—streaming services, dining out, and unused subscriptions—must pause immediately. Every single dollar you free up goes directly into an emergency catch-up pool. You cannot negotiate effectively with a lender until you know the exact dollar amount you can hand them each month.
Step 3: Request a Formal Short-Term Hardship or Forbearance Plan
If your budget review shows that you cannot make a full catch-up payment right away, do not panic. Lenders handle short-term financial setbacks through formal loss mitigation programs.
The two most common tools for a first-time missed payment are payment forbearance and a repayment plan.
A forbearance agreement allows you to reduce or suspend your monthly payments for a specific period, usually between one and three months. This does not erase the debt, but it temporarily stops the clock, halts late fees, and prevents any default notices. A repayment plan, on the other hand, takes your overdue amount and splits it into smaller pieces spread across several future payments. For example, if your missed payment was $400, the lender might allow you to pay an extra $100 per month for four months until you are fully caught up.
To qualify for these programs, you will need to submit a basic hardship package. Keep your paperwork organized and easy to read:
- A brief hardship letter: A single page explaining what caused the temporary shortfall (such as a temporary medical leave, unexpected home emergency, or seasonal reduction in hours).
- Proof of current income: Your two most recent paystubs or bank statements showing that cash flow has stabilized.
- A simple monthly budget: A clear breakdown showing that your income covers your basic living costs plus the proposed modified payment.
Submit these documents promptly through your lender's secure online portal. Always keep copies for your own records and note the date and time of every upload.
When you present a clean, organized hardship request, you change the dynamic completely. You move yourself out of the "delinquent borrower" category and into the "active resolution" category, keeping your home secure while you regain your financial footing.
Strategic Tactics to Safeguard Your Property Over the Long Haul
Navigating the early days of a late payment buys you immediate breathing room. However, you also need a durable strategy to make sure this situation never catches you off guard again.
Experienced financial planners use specific techniques to stabilize troubled home loans. Here are the advanced moves you can use right now to build a lasting defense around your home.
Explore a Full Mortgage Consolidation
If your credit score is still intact, you can look into rolling both of your home loans into a single primary mortgage. This process is known as a debt consolidation refinance.
When you hold two separate mortgages, you must manage two due dates, two servicing portals, and two interest rates. If the interest rate on your home equity loan is variable, your monthly payment can jump unpredictably whenever benchmark rates rise.
By refinancing both balances into one fixed-rate loan, you lock in a single predictable payment. This move often lowers your overall monthly outlay and eliminates the risk of an aggressive second lienholder threatening your property. To see if you qualify, check your home's current loan-to-value ratio. Most conventional lenders require you to retain at least twenty percent equity across the new total loan balance.
Negotiate a Formal Loan Recast or Term Extension
If refinancing is out of reach due to recent credit dings, ask your current lender about a loan recast or a term extension. These are powerful loss mitigation options that many borrowers never hear about. In a term extension, your lender agrees to stretch your remaining loan duration. For example, if you have seven years remaining on a ten-year home equity loan, the lender might stretch that balance across fifteen years.
This simple adjustment immediately lowers your required monthly bill. While you will pay more total interest over the life of the loan, the immediate reduction in monthly costs can keep you from losing your property. A loan recast works a bit differently. If you can scrape together a small lump sum—such as a tax refund or money from selling an extra vehicle—the lender re-amortizes your balance. They keep your interest rate and remaining months the same, but recalculate your monthly bill to a much lower number. That lower payment makes monthly budgeting far easier to sustain over time.
Create a Protected Emergency Buffer Account
A primary reason homeowners miss a loan payment is relying on a single checking account for all household expenses. When everyday bills pile up, the money reserved for your home equity loan disappears before you even notice. Open a separate, dedicated savings account at a completely different bank or credit union. Make sure this new account is not connected to your daily debit card.
Set up an automated direct deposit from your paycheck to send a set amount of cash into this account every payday. This money is your home protection buffer, and it exists for one reason only: to cover your mortgage obligations if your main income dips. Aim to build a reserve that covers at least two full months of housing payments. Having that buffer prevents an unexpected medical bill or plumbing emergency from jeopardizing your home. Review this reserve account every quarter to make sure it remains untouched. Treating your housing obligations as untouchable expenses is the most reliable way to maintain long-term stability.
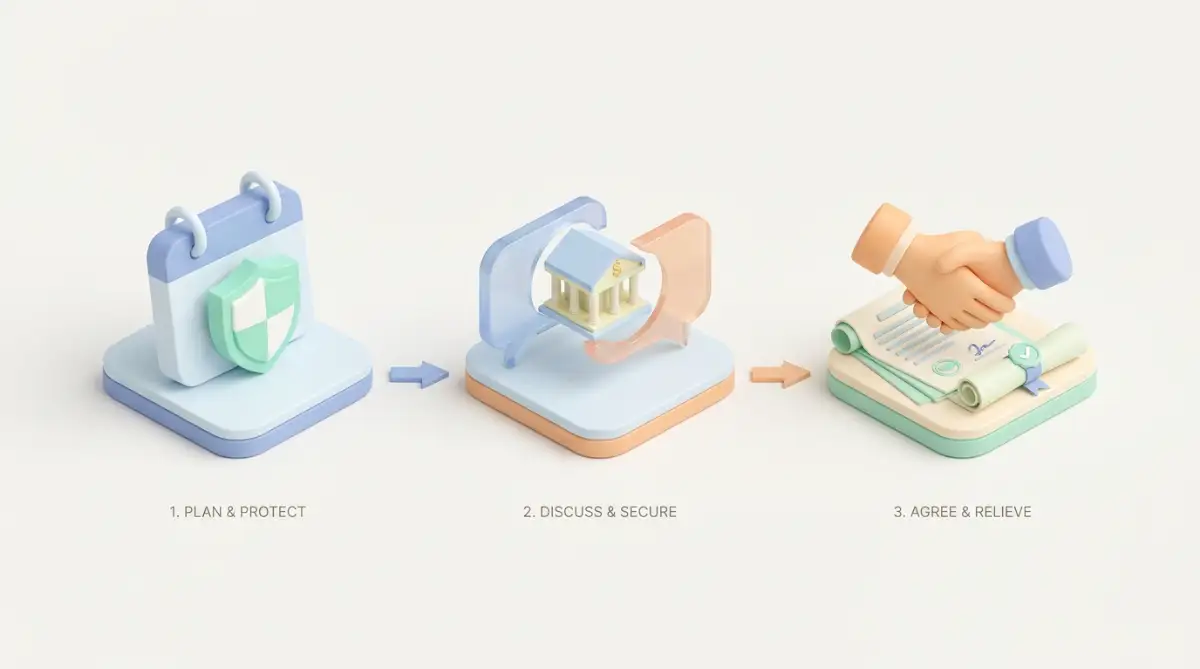
Five Dangerous Traps That Make a Missed Payment Far Worse
When you fall behind on a loan, panic often leads to rushed decisions. Desperate moves usually create much bigger financial hazards than the original late payment itself.
To protect your home and your financial future, steer clear of these five common mistakes.
1. Using High-Interest Credit Cards to Pay the Loan
Borrowers often use credit card cash advances to make a late loan payment. While this might stop the bank's phone calls for thirty days, it is simply swapping a manageable loan for high-interest toxic debt. Credit card cash advances often carry interest rates higher than twenty-five percent, and the interest starts accumulating the very second you withdraw the cash. You also face immediate transaction fees of three to five percent. Robbing one credit line to pay another creates a rapid downward spiral. You end up with the same mortgage risk a month later, but now you also carry high-rate consumer debt that drains your paycheck even faster.
2. Going Silent and Ignoring Certified Bank Notices
The absolute worst thing you can do after a missed payment is ignore communications from your loan servicer. Many homeowners stop opening their mail because seeing collection letters causes intense anxiety. However, state and federal consumer protection laws require lenders to mail specific legal notices before they take aggressive action. These documents, often labeled as a Notice of Intent to Accelerate or a Right to Cure Notice, contain strict legal deadlines.
These letters lay out the exact dollar amount needed to reinstate your loan and give you a clear window—usually thirty to sixty days—to fix the problem. If you leave these letters unopened, you throw away your legal right to dispute fees or request workout options. Always open every envelope from your lender on the day it arrives. Keep every letter, envelope, and timestamped document filed in a dedicated folder for easy reference.
3. Falling for Foreclosure Rescue Scams
Unscrupulous operators constantly scan public county records looking for homeowners who have received default warnings. They reach out through urgent letters, text messages, or uninvited phone calls,