
The Reality of Financial Pressure
I remember opening my first student loan bill while sitting on the floor of my empty apartment, feeling completely sick to my stomach. I had just lost my part-time job, and paying that huge amount felt like a cruel joke. I spent months dodging their calls because I was so scared, but hiding only made my daily anxiety much worse.
When student loan bills arrive, they often feel like a heavy weight on your shoulders. You might have had a solid plan when you graduated, but life changes quickly. A job loss, an emergency expense, or a sudden change in income can make those monthly payments feel impossible.
Many people fall into the trap of ignoring the bills, hoping they will go away. This is the most dangerous mistake you can make. The goal of this guide is to show you that there are paths forward, even when your budget feels broken.
Why Silence is Your Biggest Enemy
When you stop communicating with your loan provider, you lose your options. Lenders have specific programs designed for people who are struggling, but they only work if you reach out.
- Avoid Defaulting: Defaulting hurts your credit score for years and makes it hard to rent an apartment or buy a car.
- Take Control Early: The sooner you talk to your lender, the more options you have to adjust your payment.
- Protect Your Future: Dealing with this now saves you from legal stress and aggressive collection calls later.
Step 1: Contact Your Loan Servicer Immediately
The very first thing you should do is call your loan provider. They are not the enemy; they are the people who manage your account. You do not need to be embarrassed, as they deal with thousands of people in your exact situation every single day.
Be honest about your financial situation. Explain that your income has dropped or that you have experienced a specific hardship. Ask them directly: "What are my options for a reduced or paused payment?" Most lenders have programs designed to help you. Writing down the name of the person you spoke with and the date of the call is a smart practice. This keeps a record of your proactive effort to handle the debt.
Step 2: Explore Income-Driven Repayment Plans
If you have federal student loans, you should look into Income-Driven Repayment (IDR) plans. These plans adjust your monthly payment based on how much money you earn, not how much you owe.
In some cases, your payment could even be lowered to zero dollars per month. This is a massive relief when you are struggling to pay for basic needs like rent and food. You will need to submit some documents regarding your income, but the process is well worth the effort. Check your official government student aid website to see which plans you qualify for. Switching to these plans can turn a stressful bill into something manageable. It is a tool designed for your success, so do not hesitate to use it.
My biggest mistake was assuming I made too much money to get any real help from an income-driven plan. Once I finally swallowed my pride and applied, my monthly payment dropped by more than half. Do yourself a big favor and check your options today, even if you think you will not qualify.
Step 3: Understand Deferment and Forbearance
Sometimes, you just need a temporary break. Deferment and forbearance are two ways to pause your payments for a short time. This gives you room to breathe while you search for a new job or recover from an emergency.
Keep in mind that while payments are paused, interest may continue to grow on your loan balance. This means the total amount you owe could increase over time. Use these options as a short-term bridge, not a long-term solution. Always confirm with your lender how long you can pause your payments. Knowing your limits helps you plan for the future. Use this extra time to rebuild your budget so you can resume payments later.
Mistakes That Make Debt Worse
Avoiding these common pitfalls will keep your financial profile much healthier.
- Prioritizing Wrong Debts: Do not pay a credit card bill while ignoring your student loans if the student loan has worse consequences for default.
- Taking Out High-Interest Loans: Avoid taking out "payday loans" to pay off student loans. This creates a cycle of debt that is very hard to break.
- Waiting Until the Last Minute: Contacting your lender after you have already missed a payment is much harder than doing it before.
- Ignoring Your Budget: Even if you cannot pay the full amount, track your spending. Knowing where your money goes is the first step to regaining control.
- Losing Contact: Always keep your email and phone number updated with your loan provider so you never miss a warning letter.
Regaining Your Financial Freedom
Managing student loans is not a measure of your worth as a person. It is simply a financial challenge that requires a strategy. You have options, and you have the power to protect your credit score. Start by making that first call to your lender today. Every small step you take is a win. You are building a stronger future for yourself by facing this head-on. Take a deep breath and start your recovery today.
Step 4: The Secret of Loan Consolidation
If you are feeling confused about how to safely combine your loans without paying extra fees, watch this quick video breakdown before moving on to the rest of the guide.
If you have multiple student loans with different interest rates and due dates, managing them can be a nightmare. You might feel like you are chasing different deadlines every single week. Loan consolidation is a powerful tool to simplify your life.
By combining several federal loans into one single loan, you get one monthly payment. This makes budgeting much easier because you only have one target to focus on. Organization is the first step toward financial peace. However, check the math before you combine them. Sometimes the interest rate on a consolidated loan is the weighted average of your previous loans, which is usually a fair deal. Make sure the new payment plan fits your current income.
Step 5: Automate for Success and Small Perks
Once you set up a payment plan you can actually afford, set it to automatic payments. Most lenders offer a small interest rate discount, often 0.25%, if you use auto-pay. It might seem small, but it adds up over the life of the loan. Automation also removes the "human error" factor. You will never have to worry about forgetting a date or being a day late. It protects your credit score automatically.
Building Long-Term Financial Habits
To keep your finances in check for the long haul, you need to treat your debt like a regular utility bill. Do not view it as a punishment for your education. View it as a commitment to your own growth.
- Audit Your Expenses: Every quarter, look at where your money is going. Small daily expenses often hide in plain sight.
- Build a Buffer: Try to save even a tiny amount each month in an emergency fund. This way, if your income drops again, you are not starting from zero.
- Keep Your Contact Info Current: Always update your email and phone number with your lender. You never want to miss an important update about your account status.
Staying consistent is more important than paying a huge amount once. Consistency builds trust with your lender and keeps your credit report looking clean and professional.
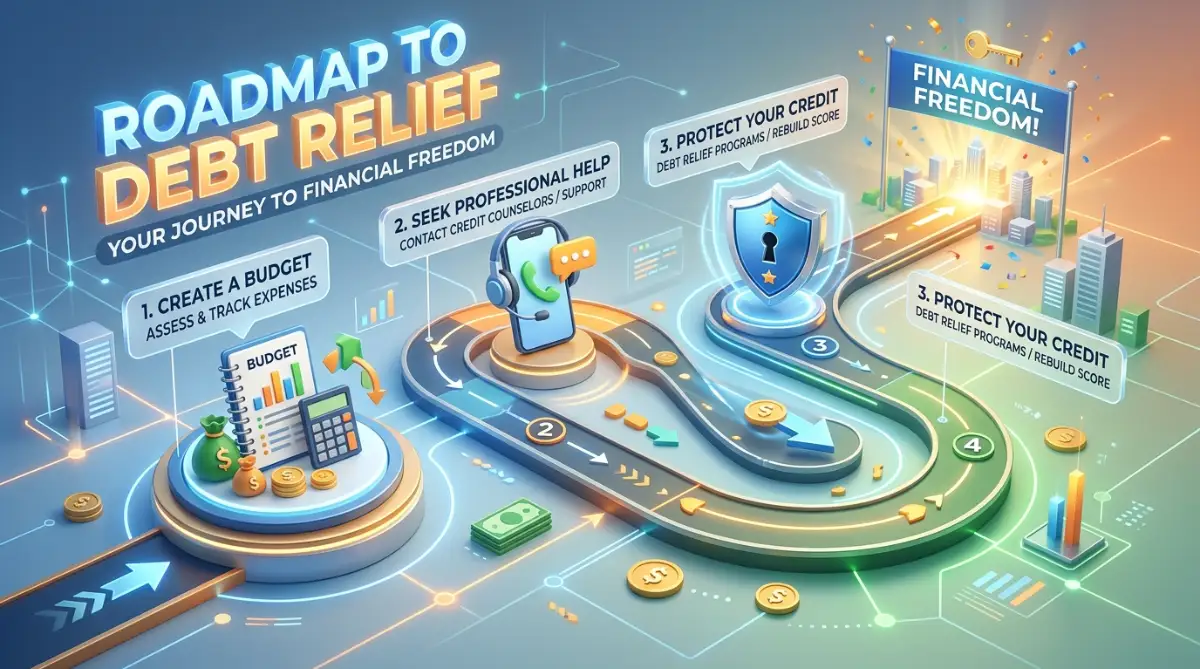
Traps That Lead to Financial Stress
Even with good intentions, people often trip over the same hurdles. Being aware of these pitfalls can save you from a lot of unnecessary pain.
- Ignoring Late Notices: When you get a letter or email from your lender, read it immediately. Ignoring it does not make the debt disappear.
- Prioritizing Wants Over Needs: Skipping a loan payment to buy something non-essential is a slippery slope. Always pay your debt obligations before choosing luxury items.
- Choosing the Longest Repayment Term: While a long term makes monthly payments look cheap, you pay much more in interest over time. Always aim to pay more whenever you have a little extra money.
- Forgetting to Recertify: Income-driven plans often require you to prove your income every year. If you forget to do this, your payment could skyrocket unexpectedly.
- Applying for New Debt: Taking on a high-interest car loan or credit card debt while struggling with student loans is a recipe for disaster. Focus on one debt at a time.
Missing these small details can result in late fees, interest spikes, and lasting damage to your reputation. Be disciplined and keep a calendar specifically for your financial commitments.
Your Path to a Debt-Free Future
You have the power to turn your financial situation around. It takes patience, honesty, and a clear plan to navigate the world of student loans. You are capable of handling this.
Start by taking the small actions we discussed today. Talk to your lender, look at your budget, and choose the plan that gives you the most peace of mind. Small steps lead to big changes over time.
Remember that you are not alone in this journey. Thousands of people face these exact challenges and find their way out every single day. Keep your focus on your goals, stay organized, and move forward with confidence. Looking back, picking up the phone to finally face my debt was the scariest but best thing I ever did for my peace of mind. You do not have to live with this heavy cloud hanging over you anymore. Take that very first small step today, and I promise you will feel so much better tomorrow.


