
Why Good People Keep Getting Bad News on Their House Loan Applications
I know exactly how much it stings when the bank says "no" to your house loan. You probably spent weeks imagining your family in that new living room, only to have a computer system flag your application. But here is the thing I learned the hard way: a rejection is almost never a permanent "no." It just means we need to fix a few hidden math problems on your paperwork. Let me show you how to clean up your file so your next application gets an easy approval.
So, you got the dreaded "no" from your lender. It honestly sucks, doesn't it? Before you start thinking your financial life is completely over, take a deep breath. Getting denied for a mortgage rarely means you are out of the game forever. Most of the time, it just means you triggered a hidden red flag in their system. I want to show you exactly what lenders look for behind closed doors, and more importantly, how you can fix your file so your next application gets an easy "yes." You found the house. You pictured the kitchen, the backyard, the morning light. Then the lender called, and your house loan application was rejected.
I still remember sitting in my car, staring at the steering wheel, when my phone rang and the loan officer said "no" to my dream home. I felt completely crushed and honestly a little embarrassed, assuming my finances were a lost cause. It took me months of stress to figure out that I was not a failure at all—I just didn't understand the quiet rules lenders used to judge my file.
The Real Struggle Behind a House Loan Rejection
Why Your Loan Got Blocked & What to Do Next
Your Fast-Track Recovery Plan
-
Ask your lender for a written reason for the rejection so you know exactly what to fix.
-
Pay off tiny debts (like small credit card balances) to instantly improve your debt-to-income ratio.
-
Keep your bank accounts boring—no sudden large cash deposits for at least 60 days before applying.
-
Check your own credit report for silly mistakes that might be holding your score down.
- Credit over Down Payment: Your payment history matters way more than the cash you saved up.
- Watch the DTI: Pay off those small, annoying debts (like a $50/month personal loan) to quickly drop your debt-to-income ratio.
- Paper Trails: Don't move large amounts of money around right before applying; lenders hate unexplained cash.
- Always Ask Why: Never accept a generic rejection. Demand a specific, written reason from your loan officer so you know exactly what to fix.
- Bad advice spreads fast. A friend says "just apply everywhere," so you do, and each rejected application hurts your credit score a little more.
- Online articles often skip the boring but important parts, like how a single late payment from two years ago can still show up on your report.
- Loan officers are busy. They rarely explain the "why" behind a rejection, so you are left guessing and repeating the same mistakes.
How Rejection Affects Your Peace and Confidence
- You start doubting your financial decisions, even the good ones. Saving for years suddenly feels pointless.
- Family conversations turn tense. A partner may blame you, or you may blame yourself, even when the problem was a simple document error.
- Your confidence drops when you apply again. You hesitate, delay, and sometimes give up on a goal you worked years to reach.
Here is what most people never hear: a rejection is not a final answer. It is a signal. It tells you exactly where the weak spot is, if you know how to read it.
Lenders are not judging your worth. They are managing risk. Once you understand their checklist, you can fix almost anything on it.
The problem is that nobody hands you that checklist upfront. So you learn by failing, which is the most expensive way to learn.
This guide exists to change that. We will walk through the real reasons house loan applications get rejected, and we will do it in plain, simple language.
No jargon. No scare tactics. Just the facts you need, explained the way a good friend would explain them over coffee.
By the end, you will know exactly what to check before you apply again, and you will feel calm instead of confused.
If you are a visual learner, watch this quick video to see the exact red flags loan officers look for first, and then keep reading below to learn how you can easily fix every single one of them.
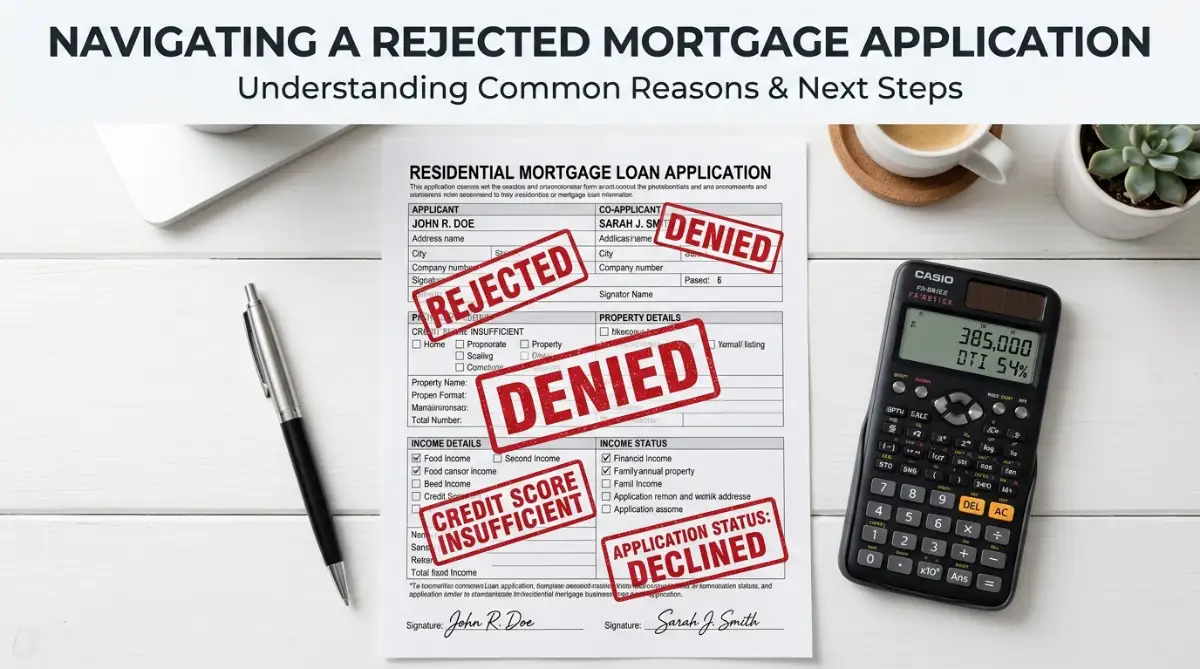
The Hidden Checklist Lenders Use Before They Say Yes
Quick Action Guide: Turning a "No" Into a "Yes"
- Demand answers: Always ask your lender for the exact, written reason your loan was denied so you know what to fix.
- Check the math: Wipe out small monthly debts (like a personal loan or credit card balance) to lower your Debt-to-Income (DTI) ratio fast.
- Track your cash: Stop moving large amounts of money around before applying. Lenders want a clean, 60-day paper trail for your bank accounts.
- Review your report: Pull your credit reports today and dispute any old errors before a loan officer spots them.
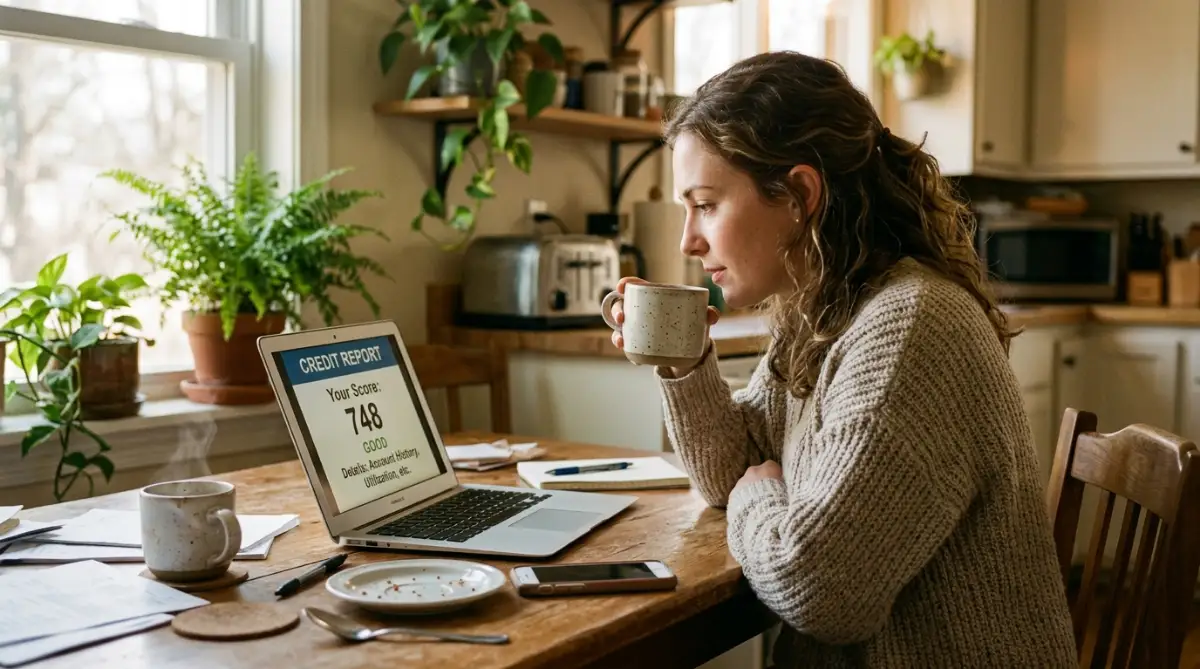
Most people obsess over the down payment. Lenders look at your credit report first.
Your credit report is a history of how you handled borrowed money. It shows payments, balances, and how long you have used credit.
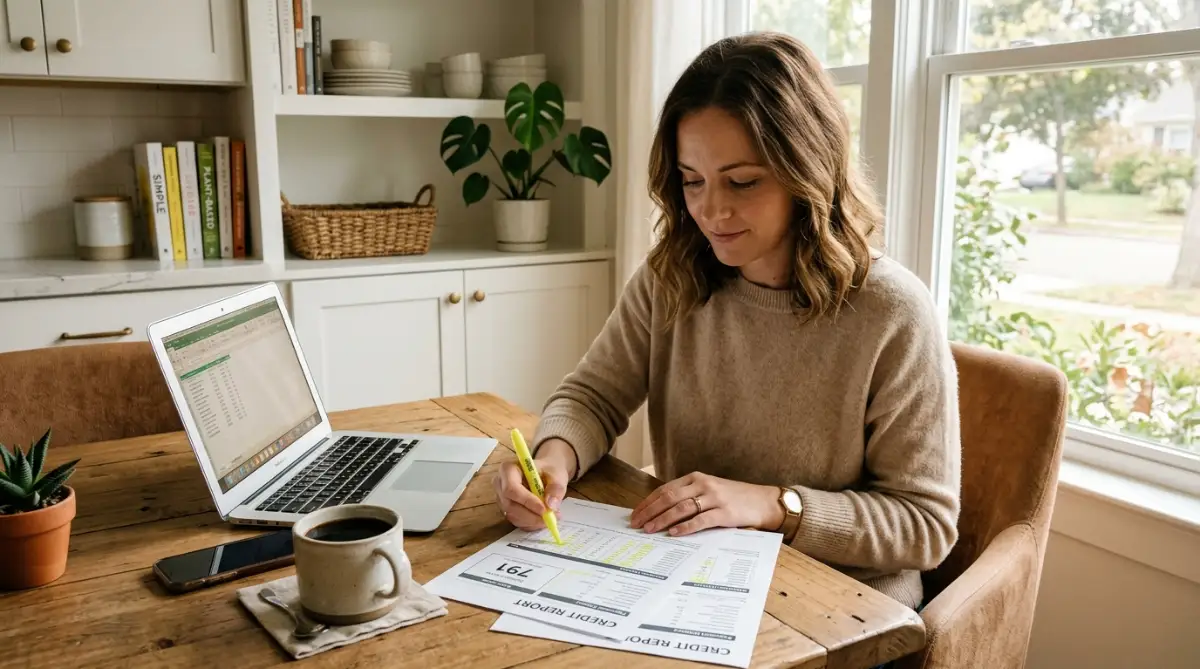
Pull your report from all three major bureaus. Read every line. Look for errors, old collections, and payments marked late.
One wrong entry can drop your score by dozens of points. Dispute anything that looks incorrect, in writing, with proof.
Think of it like a school report card. You cannot fix a bad grade you never saw. So look first, then act.
Keep Your Debt-to-Income Ratio Below the Danger Line
Lenders compare your monthly debt payments to your monthly income. This is your debt-to-income ratio, or DTI.
If you earn $5,000 a month and pay $2,000 toward debts, your DTI is 40 percent. Many lenders prefer 36 percent or lower.
Here is a simple analogy. Imagine carrying a backpack. At some point, adding one more book makes you fall over. Lenders look for that tipping point.
- Pay down credit cards and avoid new car loans before you apply. $10,000 a month, I can easily afford a $4,000 mortgage.
- Fact: Lenders look at your Gross income versus All debts. If you have a $600 car payment, $400 in student loans, and $300 in credit card minimums, that $4,000 mortgage suddenly pushes your DTI over 50%. You become too risky to approve. Always calculate your existing debts first!
-
Real-Life Scenario: The Car Loan Trap
What happened: My friend Mark applied for a mortgage on a Friday. On Saturday, he bought a new truck because his old one broke down.
The result: The bank pulled his credit one last time before closing, saw the new $600 monthly truck payment, and canceled his home loan instantly. His debt-to-income ratio shot up overnight.
The lesson: Never, ever buy a car or open a new credit card until you actually have the house keys in your hand!
Your "Ask Why" Phone Script
Not sure what to say to your lender after a rejection? Use this exact script:
"Hi [Name], I received the denial notice. I want to fix my financial file and apply again when I am ready. Can you please send me a direct email listing the exact reasons my file was flagged? This will help me know exactly what to pay off or correct."
When I first applied, my biggest mistake was keeping a small personal loan open just because the monthly payment felt cheap. I didn't realize that paying off that remaining $1,500 balance would instantly drop my debt-to-income ratio and turn my rejection into an easy yes. Always wipe out those tiny, annoying debts before your lender even looks at your paperwork!
Do not open new credit accounts right before applying. Each new account lowers your average account age and adds a fresh inquiry.
Fix Documentation Errors Before They Cost You the Loan
Paperwork is boring, and that is exactly why it sinks so many applications.
Lenders need proof of income, identity, employment, and assets. If any document is missing, blurry, or outdated, your file gets flagged.
Common mistakes include:
- Pay stubs older than 30 days
- Bank statements with missing pages
- Name spelling differences between your ID and your pay stub
Unexplained large deposits
The "Do Not Touch" Money Rules
-
Rule 1: Don't deposit random cash you had hiding under your mattress. Banks hate untraceable money.
-
Rule 2: Don't move large amounts of money between your savings and checking accounts right before applying.
-
Rule 3: If your parents give you money for a down payment, get a signed "gift letter" from them so the bank knows it isn't a secret loan you have to pay back.
The "Mattress Money" Mistake
- I recently talked to a homebuyer who deposited $8,000 in cash into their checking account right before applying. They had saved this money at home for years. The lender completely rejected the application because there was no paper trail to prove where the cash came from (lenders call this "unseasoned funds"). If you have cash saved up, deposit it into your bank at least 60 to 90 days before you apply for a loan so it blends into your normal bank statements.
Treat your application like a passport renewal. One missing page means the whole thing comes back.
Double-check every page before you submit. Ask a friend to review it too. Fresh eyes catch what tired eyes miss.
If you are self-employed, prepare two years of tax returns and a profit-and-loss statement. Lenders scrutinize variable income much more closely.
Understand How Employment History Shapes Your Approval
Lenders want stability. A steady job history signals that income will keep coming.
Job hopping every few months raises questions, even if your salary grows. Two years in the same field is a comfortable benchmark.
If you recently changed careers, prepare a short written explanation. Keep it factual and calm.
A letter of explanation is not an admission of guilt. It is context, and lenders appreciate context.
Freelancers and gig workers face extra checks. Keep clean records, separate business and personal accounts, and file taxes on time.
Watch for Hidden Red Flags in Your Banking Activity
Your bank statements tell a story, and lenders read between the lines.
Large, unexplained cash deposits look suspicious. So do bounced checks and repeated overdraft fees.
If a family member gifted you money for the down payment, get a gift letter. It confirms the money is not another loan.
Lenders must verify where your down payment came from. Untraceable funds can delay or kill an approval.
Keep your accounts clean for at least three months before applying. Avoid moving large sums without a paper trail.
Small habits matter here. Pay bills on time, keep a buffer in your account, and avoid gambling transactions on your statement.
Do Not Ignore the Property Itself
Sometimes the problem is not you. It is the house.
Lenders order an appraisal to confirm the home is worth the loan amount. If the appraisal comes in low, the deal can fall apart.
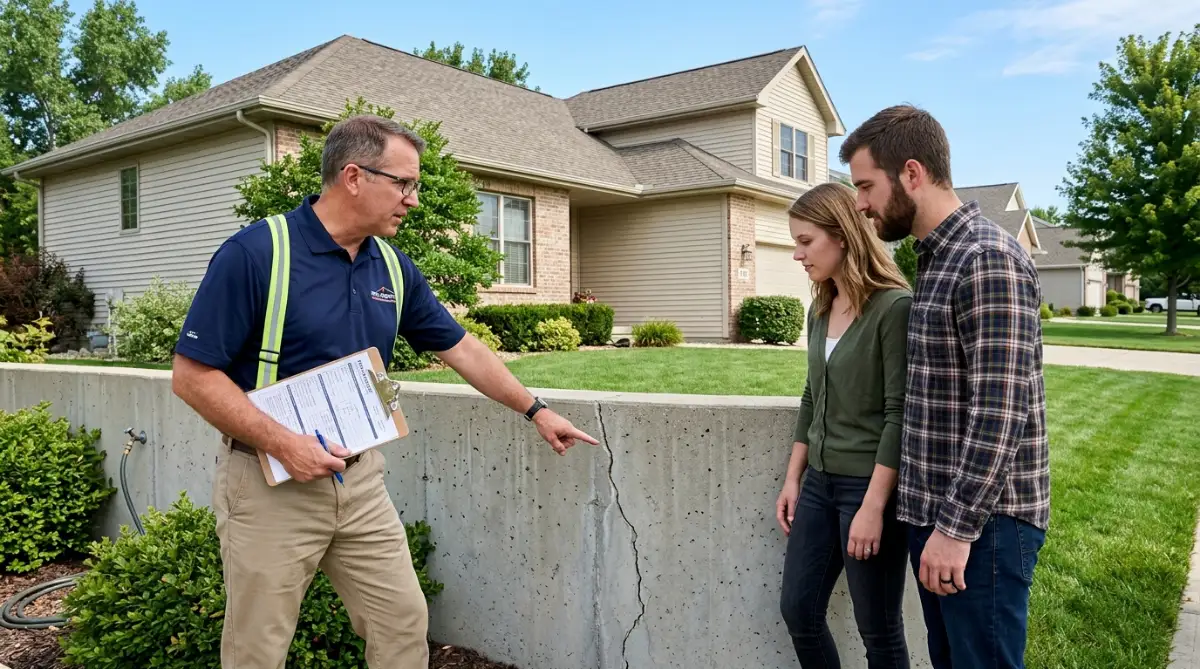
The property must also meet basic condition standards. Major roof damage, foundation cracks, or safety issues can block financing.
A fixer-upper sounds romantic until the appraisal report arrives. Ask questions early about the home's condition.
If you are buying in a flood zone, expect extra insurance requirements. These add to your monthly cost and affect approval.
Walk through the property with a professional inspector before you fall in love with it. Emotions are expensive in real estate.
Why Multiple Applications Hurt More Than They Help
Every time a lender pulls your credit, it leaves a mark called a hard inquiry.
One or two inquiries are normal. Ten in a month looks desperate to lenders, even if you are just shopping around.
Rate shopping is fine if you do it inside a short window. Most scoring models treat inquiries within 14 to 45 days as one.
Do your research first. Get pre-approved by one trusted lender, then compare offers carefully.
The Emotional Side Nobody Talks About
Rejection stings, and pretending it does not is unhelpful.
Give yourself a day to feel disappointed. Then open your documents and start fixing the real issues.
A rejected application is data, not a verdict. It tells you where to improve and what to prepare next time.
Talk to your partner openly. Money stress grows in silence and shrinks in honest conversation.
Many successful homeowners were rejected once or twice before they got the keys. The difference is they asked why and tried again.
Your Next Move Starts Today
You do not need to be perfect. You need to be prepared.
Start with your credit report. Then check your DTI, your documents, and your bank statements.
Fix one thing at a time. Small steps build momentum, and momentum builds confidence.
Preparation beats luck every single time. Lenders approve borrowers who look ready, not borrowers who look hopeful.
Take a deep breath. Open that folder. Your house is still waiting, and now you know the way forward.
Smart Moves That Turn a Rejected Application Into an Approved One
Ask the Lender for a Written Rejection Reason
Most people accept a "no" and walk away. That is the biggest mistake you can make.
Call the lender and ask for the specific reason in writing. You have a right to know what triggered the decision.
Sometimes the answer is simple. A missing pay stub. An outdated bank statement. A name mismatch.
You cannot fix a problem you cannot name. Get the reason, write it down, and treat it as your to-do list.
If the lender refuses to explain, that tells you something too. A lender who hides the reason may not be the right partner for you.
Consider it like a doctor's diagnosis. You would never accept "you are sick" without asking which illness and what treatment.
Write a Strong Letter of Explanation
Lenders love context, especially when something on your file looks odd.
A letter of explanation is a short, honest note that clarifies a specific issue. It is not an apology. It is information.
Say you had a medical emergency two years ago that caused late payments. Explain the situation, show recovery, and prove you are back on track.
Keep it to one page. Use clear sentences, attach supporting documents, and avoid emotional language.
Here is a quick structure that works:
- State the issue in one sentence
- Explain the cause briefly
- Show what changed since then
- Provide proof, such as new payment records
Think of it as a cover letter for your finances. It introduces your story before the numbers speak.
Improve Your Credit Score the Slow, Steady Way
Quick fixes rarely work, and lenders see through them. Real improvement takes months, not days.
Start by paying every bill on time. Payment history is the single biggest factor in your score.
Next, lower your credit card balances. Aim to use less than 30 percent of your available limit.
A $1,000 limit with a $900 balance looks risky. The same limit with a $200 balance looks calm and controlled.
Do not close old credit cards, even if you rarely use them. Length of credit history matters.
If you have a trusted family member with strong credit, ask about becoming an authorized user. Their good history can gently lift yours.
Save a Bigger Down Payment Buffer
A larger down payment lowers the lender's risk and your monthly payment.
It also gives you room to absorb surprises. Appraisal gaps, closing costs, and moving expenses add up fast.
Aim for at least 20 percent if you can. Below that, you may pay private mortgage insurance, which adds to your cost.
If 20 percent feels far away, do not panic. Even an extra 5 percent strengthens your file and your negotiating power.
Picture it like packing for a long trip. The more you prepare, the less you panic when plans change.
Choose the Right Lender, Not the Fastest One
Not all lenders treat borrowers the same. Some are strict. Some are flexible. Some specialize in first-time buyers.
Credit unions often offer better terms for members. Local banks may look at your full story, not just a score.
Shop with purpose, not desperation. Talk to two or three lenders and compare their requirements side by side.
Ask each lender what would make your file stronger. Their answers will teach you more than any blog post.
The right lender will explain the process, return your calls, and treat you like a person, not a file number.
Keep Your Financial Life Quiet During the Process
Once you apply, your finances should go into a quiet zone.
Do not change jobs. Do not finance a car. Do not co-sign a loan for a friend. Do not make large, unexplained deposits.
Lenders re-check your file before closing. A new debt or a sudden job change can undo an approval.
If you must change something, tell your loan officer first. Surprises kill deals faster than bad numbers.
Think of your application like a glass of still water. Any shake makes ripples, and ripples draw attention.
Applying Before You Are Ready
Excitement pushes people to apply too early. They see a house, fall in love, and rush the paperwork.
A rushed application often leads to a rejection that could have been avoided with two more months of preparation.
Wait until your credit, documents, and savings are solid. A short delay beats a long denial.
Hiding Information From Your Lender
Some borrowers leave out a small debt or an old collection, hoping nobody notices.
Lenders pull your full report. They will see it. And now you look dishonest, not just risky.
Honesty protects you. Disclose everything upfront and explain anything unusual with a short letter.
Making Big Purchases Mid-Process
A new truck, new furniture, or a vacation on credit can push your debt-to-income ratio over the line.
Lenders often re-pull your credit just before closing. That new loan appears, and the approval disappears.
Freeze all major spending until the keys are in your hand. Your future living room can wait two more weeks.
Ignoring Small Errors on Your Credit Report
A single wrong digit can sink your score. It happens more often than you think.
People assume the report is always right. It is not. Bureaus make mistakes, and those mistakes cost you money.
Dispute errors in writing with proof. Follow up every 30 days until the item is corrected or confirmed.
Using the Wrong Type of Loan for Your Situation
Some buyers pick a loan because a friend used it. Others pick the one with the lowest advertised rate.
The right loan depends on your income type, credit history, down payment, and long-term plans.
An FHA loan, a conventional loan, and a VA loan all serve different people. Match the loan to your life, not to a headline.
Choosing wrong can mean higher fees, stricter rules, or a rejection you did not deserve.
Your Fresh Start Begins With One Small Step Today
A rejected house loan application is not the end of your story. It is a checkpoint, and checkpoints exist to keep you safe.
You now know what lenders look for. You know the hidden checklist, the common traps, and the smart moves that fix them.
Take one action today. Pull your credit report. Call your lender. Write that letter of explanation.
Small, steady steps beat big, desperate moves every time. Lenders approve prepared people, and preparation is a habit you can build.
Looking back, getting that first painful rejection was actually a hidden blessing because it forced me to finally take control of my money. If I can turn my messy bank statements and confusing credit report into a real set of house keys, I promise you can do this too. Take a deep breath, grab a cup of coffee, and pull your credit report today—your future self will be so glad you started now.
Your home is still out there. The kitchen, the backyard, the morning light are all waiting.
You are closer than you think. Open that folder, make the call, and take the next step.


