
My Rude Awakening: When a Good Salary Was Not Enough
A few years ago, I landed a high-paying job and immediately walked into a bank thinking I was guaranteed an easy loan approval. Instead of walking out with a check, I was blindsided when the loan officer rejected me simply because I had changed companies twice in six months. That painful wake-up call taught me that lenders care far more about how long you have held your seat than how big your direct deposit looks.
You might think a fat paycheck is your golden ticket to a car loan or a new home. I used to believe the same thing until a bank officer rejected my application—not because I was broke, but because I was 'unstable.' Your income is only half the story; the other half is a hidden game of employment history that most people lose before they even start. Let's look at why your boss's name and your time on the clock matter more to lenders than the actual numbers on your paystub.
Then, I decided to apply for a modest personal loan to fix up my aging roof. I walked into the local bank feeling completely confident, almost arrogant, about my chances of getting the money. The loan officer smiled, took my application, and ran my details through their system. To my absolute shock, my application was flat-out rejected on the spot. My jaw actually dropped, and I felt a hot wave of embarrassment wash over me in the middle of that quiet office. It turns out, my shiny new job title meant absolutely nothing to them.
Why? Because I had switched careers three times in the past few months. I had zero idea that moving to a higher-paying job could actually ruin my chances of getting approved.
The Hidden Rules of Earning and Borrowing
The 3 Stability Secrets to Save Your Next Loan
- Time is Money: Lenders prefer a lower salary with 2 years of history over a huge salary with only 2 months of history.
- The DTI Trap: Your paycheck size doesn't matter if your monthly bills take up more than 36% of your income.
- Don't Quit Yet: Switching careers right before applying for a mortgage is the fastest way to get rejected, no matter how much more the new job pays.
Most people confuse their credit score with their overall borrowing power. You can have a perfectly flawless score but still get denied for a mortgage or an auto loan. Your credit score only tells lenders how you handled debt in the past. It shows them if you pay your bills on time or if you max out your credit cards.
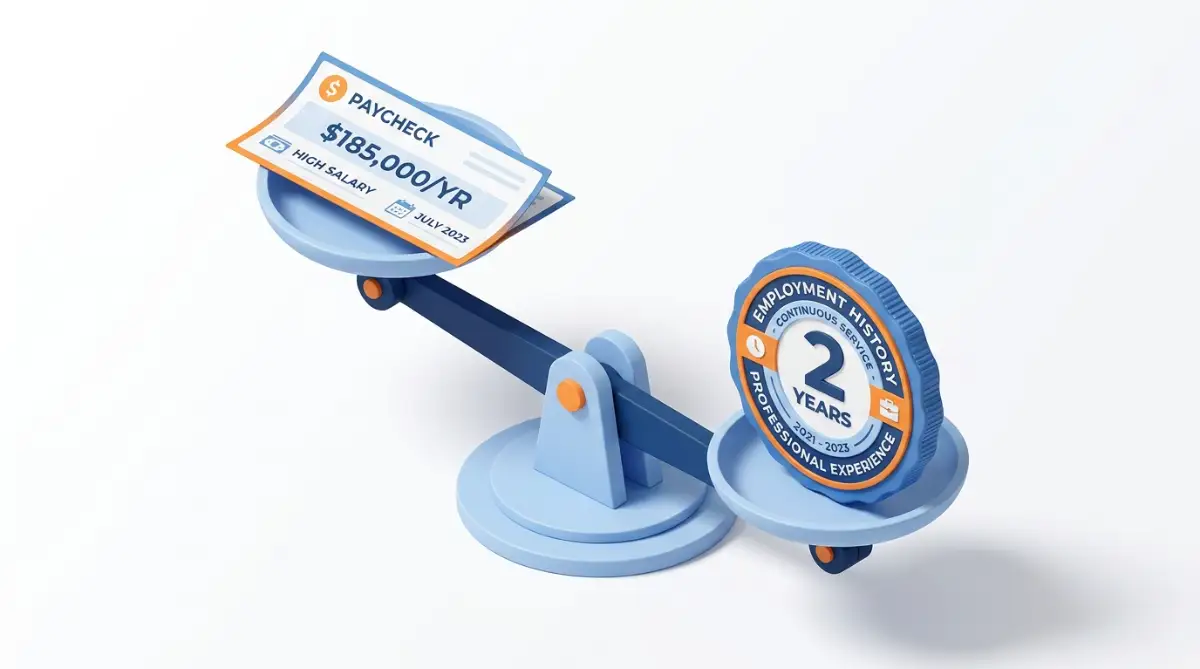
But that three-digit number tells them absolutely nothing about your ability to pay them back tomorrow. This is exactly where your employment history steps into the spotlight. Lenders want to see a reliable machine that generates cash predictably and steadily. They view your job as the engine that will fund their monthly payments. If your engine looks like it might break down or change parts every few months, they get extremely nervous. Banks hate surprises, and unpredictable employment is the biggest surprise of them all.
The Lender’s Secret Scorecard: What They Really See
While you see a career upgrade, the bank sees a risk. Here is how they grade your professional choices:
Why Longevity Matters More Than Your Paycheck
When you apply for a major line of credit, lenders typically want to see at least two years of consistent work history. They prefer you to be in the same field, if not the exact same company. Imagine you are lending a large sum of your own money to a stranger. Would you lend it to someone who has worked at the same firm for five years, or someone who changes jobs every ninety days? The answer is pretty obvious when you put yourself in their shoes.
Consistent employment proves to the underwriter that you can hold down a position and weather professional storms. It shows that you have passed multiple performance reviews and are valued by your boss. If you constantly jump from tech to retail, and then to freelance consulting, red flags fly up everywhere. Lenders instantly wonder if you have trouble committing or if you keep getting fired.
The Debt-to-Income (DTI) Reality Check
Your paycheck size does matter, but not in the way you might assume. Lenders look closely at a formula called the Debt-to-Income ratio, or DTI. This number compares how much you owe every month to how much you earn before taxes. You could be making a massive six-figure salary, but if your monthly debts eat up most of it, you look broke on paper. Here is a quick reality check: Lenders generally want your DTI to stay below 36 percent. If your car payment, student loans, and credit card minimums take up half your paycheck, getting new credit is nearly impossible.
Your job dictates the income side of this equation. If your income fluctuates because you rely on commissions or overtime, lenders will average it out over two years. They will not just look at your best month and approve you based on that high number.
Myth vs Reality: Job Hopping for Better Pay
The Myth: Switching jobs constantly to increase your salary makes you look like a highly desirable borrower. You think lenders will love your bigger paychecks.
The Reality: Frequent job changes reset the clock on your employment stability. Even if you get a huge pay bump, lenders might delay your approval until you finish your probationary period at the new company. Sometimes, underwriters will ask for offer letters, pay stubs, and even written confirmation from your new HR department. If your new position relies heavily on bonuses instead of a base salary, they might ignore that bonus income entirely for the first two years. You have to be incredibly careful when timing a job switch. If you plan to buy a house, stay put in your current role
Expert Move: The 'Bridge' Strategy
If you know you are going to switch jobs but also need a loan, get your credit approved before you put in your notice. I tell my friends all the time: your borrowing power is highest when you have a long history at your current desk. Don't trade your stability for a higher salary until the loan money is already sitting in your bank account.until the keys are safely in your hand.
I Learned This the Hard Way (My Pro Tip)
I learned very quickly that banks do not care about my future potential, they only care about my provable past. My biggest realization was that keeping an organized digital folder of my last three years of W-2s and pay stubs gave me immediate leverage. When you have your employment documentation ready to email at a moment's notice, underwriters treat you with a lot more respect and move your file to the top of the pile.
Watch This Expert Breakdown on Managing Your Finances While Switching Jobs
If you want to understand exactly how bank underwriters secretly calculate your risk when you change careers, this short guide breaks it down perfectly. Watch how easily you can prepare your profile before applying for your next big loan.
The Freelancer and Gig Worker Disadvantage
We live in an economy where side hustles and self-employment are incredibly popular. Working for yourself gives you freedom, but it creates a massive headache when proving your creditworthiness. When you are a regular W-2 employee, your taxes are straightforward and your income is predictable. When you are a 1099 independent contractor, your income looks like a wild rollercoaster to a bank.
Lenders know that self-employed businesses have high failure rates. They also know that freelancers write off a lot of expenses on their taxes to lower their taxable income. The problem is, banks use your net taxable income to calculate your borrowing power. If you made a hundred thousand dollars but wrote off sixty thousand in business expenses, the bank thinks you only made forty thousand. This simple tax trick can completely block you from getting the loan size you need.
Stability Comparison: Salaried vs Freelance
Here is a quick look at how differently lenders view these two employment types:
As you can see, self-employed individuals have to jump through burning hoops to prove they are worthy of credit. If you run your own business, you must maintain impeccable records.
How to Survive Employment Gaps
Life happens, and sometimes we lose our jobs due to company layoffs or personal health emergencies. You might be terrified that a six-month gap on your resume will destroy your financial future forever. Thankfully, underwriters are human beings who understand that layoffs happen. The key to surviving an employment gap is how you explain it.
If you can show that you used the time to gain new certifications or take care of a sick family member, lenders are often understanding. They primarily want to see that you have successfully re-entered the workforce and stabilized your income. However, if you have multiple unexplained gaps every single year, that becomes a serious pattern of instability. You must be prepared to write a formal "Letter of Explanation" detailing exactly why those gaps occurred.
Actionable Steps to Bulletproof Your Financial Profile
My Personal Rule: Whenever I plan a major career move now, I always finalize any needed loans months before handing in my two weeks' notice. Underwriters love seeing steady, unbroken time on the job, so keeping your current desk until your loan funds actually clear will protect you from sudden rejections.
Now that you understand how lenders think, you can start playing the game to win. The very first step is to never quit your job impulsively if you know you need to borrow money soon. Plan your career moves around your major financial goals. If you want to buy a new car, get the loan approved and finalized before you hand in your resignation letter. Second, start paying down your revolving debts to improve your DTI ratio. If your employment history is slightly weak, having a very low debt burden can sometimes balance out the risk.
If you recently graduated from college and just got your first professional job, you actually have a secret advantage. Lenders often count your years in college as "employment history" if your new job is in the exact same field as your degree.
The Impact of Promotions and Raises
Getting a promotion at your current company is the absolute best-case scenario for your creditworthiness. You get a larger paycheck, which improves your debt-to-income ratio immediately. Even better, your time at the company continues to accumulate. You get the financial boost of a new job without the penalty of starting over at a new employer.
Make sure your HR department updates your official job title in their verification system. Sometimes, underwriters call to verify your position and get confused if HR still lists you as a junior associate. Always keep your paper trail extremely clean. Save your promotion letters, bonus structures, and revised contract agreements in a safe place.
Handling Part-Time Jobs and Side Hustles
Many people work a full-time job and drive for a rideshare app on the weekends to make ends meet. You might think this extra cash will help you qualify for a bigger loan. Unfortunately, lenders are very strict about side hustle income. Just like freelance work, they usually demand to see two full years of tax returns proving this side income is stable.
If you just started selling crafts online three months ago, that money does not exist in the eyes of a bank underwriter. They will entirely exclude it from your application. Do not rely on brand new side gigs to push your loan application over the finish line. Focus entirely on optimizing your primary source of steady income.
When Your Employer's Reputation Matters
Believe it or not, the company you work for can subtly influence an underwriter's decision. If you work for a massive, globally recognized corporation, lenders instantly feel a sense of security. They assume a giant tech company or a national hospital system is not going to shut down overnight. Your paycheck is viewed as highly secure and guaranteed.
On the flip side, if you work for a brand new startup with three employees, lenders might dig a little deeper. They might worry that the startup could run out of funding and leave you unemployed without warning. You cannot always control where you work, but you should be aware of this hidden bias. If you work for a fragile startup, make sure your savings account is highly funded to show you have a safety net.
Navigating the HR Verification Process
Before a lender hands over thousands of dollars, they do a final check called the Verification of Employment (VOE). This usually happens just days before your loan is officially funded.
The lender will call your employer's human resources department to ask a few specific questions. They will ask if you are currently employed, what your exact title is, and if there is any known risk of you being terminated. If you are on unpaid leave, suspended, or have already given your two weeks' notice, HR is legally obligated to tell the truth. If the lender finds out you are leaving, they will instantly freeze or cancel your loan. Never try to hide a job loss from your bank during the underwriting process. It is considered bank fraud and will lead to an automatic denial and potential legal trouble.
Creating a Long-Term Stability Strategy
To truly master your creditworthiness, you need to view your career through a financial lens. Every job hop, every gap, and every side hustle paints a picture of your reliability. Aim to build a solid foundation by staying in your primary industry for long stretches of time. If you do switch paths, understand that you might need to rent or hold of