
The Hidden Stress of Graduate Loan Repayment
I remember opening my first billing statement after graduation and feeling my stomach drop instantly. I honestly had no idea how an entry-level salary was supposed to cover both rent and those massive monthly loan amounts. That moment of pure panic is the exact reason I had to learn how income-driven options actually work before things got out of hand. Stepping out of college and into the professional world brings a wave of excitement. Yet, that initial joy often fades the moment the first student loan bill arrives in your inbox[1].
You start to wonder how a standard monthly payment is supposed to fit into an entry-level paycheck. The sheer weight of the numbers can make your chest tighten up on a regular Tuesday morning. Many graduates find themselves trapped in a cycle of financial anxiety because their monthly obligations outpace their actual earnings[1][2]. Finding a reliable way out feels like searching for a needle in a massive haystack. When you rely on random online forums or outdated advice, you end up making decisions based on fear rather than facts. This common trap leads many well-meaning borrowers straight into costly mistakes that could have been easily avoided[3].
- Misinterpreting fixed terms: Believing you have no other choice than a rigid ten-year schedule[4][5].
- Ignoring structural changes: Missing important shifts in federal lending rules that impact your monthly budget[2][5].
- Relying on hearsay: Taking financial cues from peers who are just as confused as you are.
- Procrastinating on paperwork: Waiting until delinquency hits before looking for genuine relief programs.
- Constant mental fatigue: Waking up every single day worried about upcoming due dates.
- Stifled career moves: Turning down lower-paying dream jobs because they do not cover rigid loan bills.
- Delayed life milestones: Putting off buying a car, renting an apartment, or saving for the future.
- Unnecessary shame: Feeling like financial struggles are a personal failure instead of a systemic hurdle.
Managing debt is not just about crunching numbers on a spreadsheet[6]. It takes a massive toll on your inner peace and your belief in your own future[6]. When every single dollar is spoken for before you even get paid, your confidence takes a severe hit. You begin to question your degree, your choices, and your ability to build a stable adult life. This ongoing pressure changes how you interact with the world around you. You stop planning vacations, you skip social outings, and you live in a constant state of low-grade panic[6]. The good news is that you do not have to stay stuck in this exhausting loop. Understanding how alternative structures work can completely change your financial trajectory[1][5].
By looking closely at how income-linked options are designed, you can reclaim your peace of mind[1][5]. It is all about shifting your perspective from helpless victim to informed borrower[7]. Let us break down the exact steps you can take starting today to regain control over your financial destiny[7].
A Clear Framework for Managing Your Federal Student Loans
Taking control of your educational debt requires a calm and methodical approach[2]. You do not need a finance degree to make sense of the system. You just need to follow a practical sequence that cuts through the confusing jargon[3][7]. Let us walk through three actionable steps that will help you evaluate your current standing and map out a safer path forward[4][7].
Step 1: Audit Your Loan Portfolio and Servicer Details
Before you can fix anything, you must know exactly what you owe and who holds your debt[3][4]. Log into your official federal student aid dashboard to review every single active loan[4][7].
- Identify loan types: Check whether your loans are direct subsidized, unsubsidized, or consolidation loans[1].
- Locate your servicer: Make sure you know which company currently manages your billing and customer service[4][7].
- Check interest rates: Note the specific percentage attached to each individual loan balance.
Think of this step like cleaning out a cluttered garage. You cannot organize your tools until you pull everything out into the light and see what you actually have. Knowing your baseline removes the guesswork and stops the anxiety of the unknown[6]. Write down these details in a simple notebook or a secure digital document[6]. Looking back at my own mistakes, I learned the hard way that missing a single annual recertification notice can completely ruin your monthly budget overnight. If I could go back, I would have set automatic tax data sharing from day one instead of trying to manage all that paperwork by hand.
Step 2: Compare Standard Terms with Income-Linked Structures
Once you have your numbers in front of you, it is time to look at how different repayment blueprints function[4][7]. A standard plan divides your total balance into equal monthly chunks over a fixed timeline[4].
- Assess your cash flow: Compare your current take-home pay against your mandatory monthly bills[1][6].
- Evaluate flexibility: Look at how income-linked frameworks adjust your monthly dues based on what you actually earn[1][4][7].
- Factor in family size: Understand how household dependents shift the calculation in your favor[1][4][7].
Imagine trying to wear shoes that are two sizes too small. You might be able to limp along for a little while, but eventually, it will cause real damage. Income-linked structures act like custom-fitted footwear designed to match your current financial stride[1]. They ensure your basic living costs come first before your debt demands attention[6].
Step 3: Streamline Recertification and Tax Data Sharing
If you want to see how these federal repayment calculations actually look on your screen, watch this quick step-by-step walkthrough before diving into your own paperwork!
Choosing a plan is only half the battle; maintaining it requires a yearly rhythm[5][7]. To keep your payments aligned with your earnings, you must update your financial information on a regular basis[5][7].
- Give IRS consent: Allow secure data sharing to streamline your annual income updates automatically[5][7].
- Track recertification dates: Mark your calendar well in advance so you never miss a crucial deadline[5][7].
- Monitor life changes: Keep tabs on shifts in your household size or employment status[4][5][7].
Consider this step like changing the oil in your car. It is a small, routine maintenance task that prevents major engine trouble down the road. When you automate your data sharing, you take human error out of the equation[5][7]. This keeps your account in good standing without constant administrative headaches[5][7]. By treating your debt as a manageable business project rather than an emotional burden, everything changes. You start seeing opportunities to optimize your cash flow and protect your hard-earned income[1][6]. Take it one small step at a time, and remember that informed choices always lead to better outcomes[1][7].
Step 4: Map Out Your Long-Term Debt Strategy
Moving past the basic setup requires looking at the bigger picture of your financial life. You need a clear roadmap that connects your monthly loan payments to your ultimate life goals. This means planning for major milestones like buying a home or starting a family without letting debt hold you back.
- Align career growth with repayment: Anticipate how salary raises will influence your monthly obligations over time.
- Factor in public service options: Check if your career path qualifies you for specialized forgiveness programs.
- Balance savings and debt: Build an emergency fund while keeping your monthly loan payments manageable.
Think of your debt strategy like plotting a cross-country road trip. You need to know your starting point, your destination, and where the potential rest stops are located. If you only look at the next mile, you might run out of fuel when you least expect it. Mapping out the entire journey gives you deep peace of mind.
Step 5: Leverage Annual Recertification as a Financial Checkup
Your financial life changes every year, and your student loan strategy should change right along with it. Treating your annual recertification as a yearly review helps you stay on top of your money. It is a chance to see how far you have come and adjust your sail if the winds shift.
- Review income shifts: Take note of any promotions, job changes, or side hustles you picked up over the past year.
- Assess family size changes: Update your dependent count to ensure your payment calculation remains accurate.
- Celebrate small wins: Acknowledge the progress you have made toward long-term financial stability.
Imagine checking the dashboard of your car before a long drive. You want to make sure your tires are inflated and your oil levels are right where they need to be. Annual recertification serves that exact purpose for your student loans. It keeps everything running smoothly and prevents nasty surprises from creeping up on you.
Common Pitfalls That Can Derail Your Progress
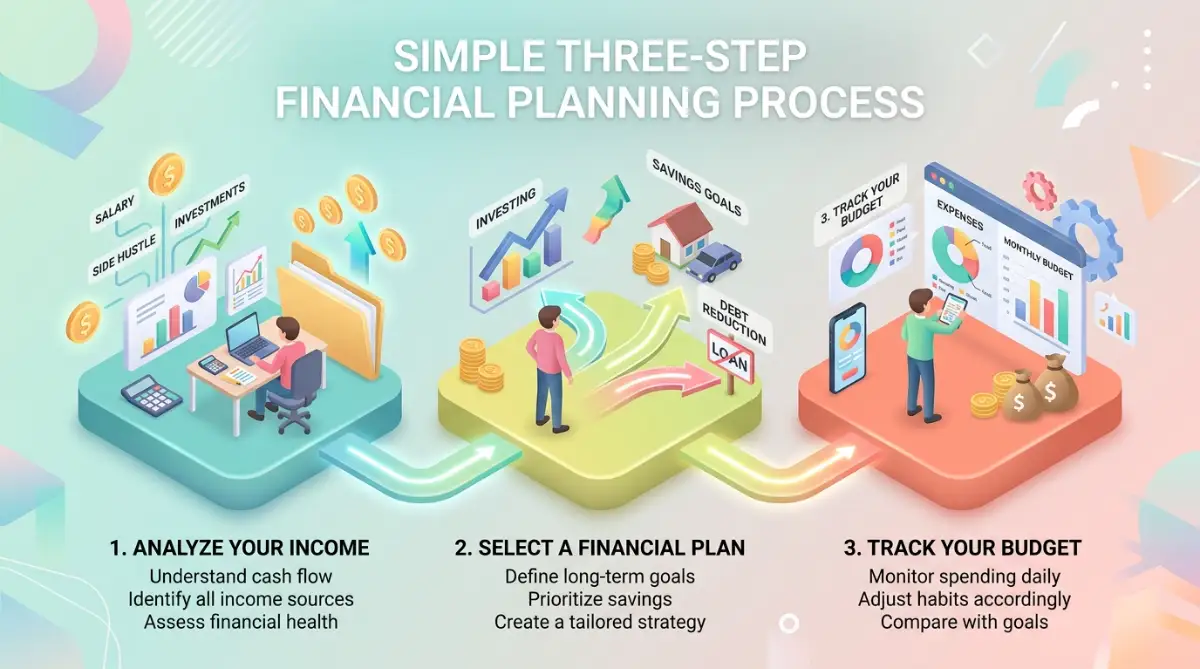
Even with the best intentions, many borrowers stumble into avoidable traps along the way. Recognizing these common missteps can save you months of frustration and extra expenses. Let us walk through five major pitfalls you should actively avoid.
Pitfall 1: Missing the Annual Recertification Deadline
One of the most damaging mistakes you can make is forgetting to recertify your income on time. When you miss this deadline, your monthly payment can skyrocket back to the standard rate overnight. This sudden spike can instantly shatter a carefully planned monthly budget.
- Set multiple reminders: Use your phone and calendar to flag the renewal date months in advance.
- Opt for automatic data sharing: Let the system pull your tax details automatically to avoid manual oversight.
- Never ignore servicer notices: Open and read every piece of mail or email your loan servicer sends you.
Pitfall 2: Focusing Solely on Lowering Monthly Payments
It is easy to get tunnel vision when looking for the lowest possible monthly bill. While a tiny payment feels great today, it might stretch out your repayment timeline for decades. This extended timeline often means you pay significantly more in total interest over the life of the loan.
- Look at total costs: Always calculate the lifetime cost of the loan, not just the monthly figure.
- Weigh forgiveness timelines: Understand how long you must remain in a program before any remaining balance is addressed.
- Balance current comfort with future goals: Find a middle ground that helps you survive today without hurting your tomorrow.
Pitfall 3: Assuming All Loan Types Qualify Automatically
Not all student loans share the same rules or benefits. Many borrowers assume federal programs apply equally to private loans taken out through commercial banks. This confusion can lead to missed opportunities and wasted effort.
- Verify loan ownership: Confirm whether your debt is federally backed or privately held.
- Read the fine print: Check the specific eligibility requirements for every program you wish to join.
- Keep categories separate: Do not mix up federal consolidation rules with private refinancing offers.
Pitfall 4: Neglecting Emergency Savings While Paying Debt
Some people throw every single spare dollar at their student loans while ignoring their cash savings. If an unexpected car repair or medical bill pops up, they have nowhere to turn. This forces them right back into high-interest credit card debt.
- Build a safety net first: Keep a small cash buffer in a separate savings account before making extra loan payments.
- Keep a balanced approach: Allocate funds for both your future self and your current peace of mind.
- Avoid financial burnout: Trying to pay off everything at once often leads to giving up entirely.
Pitfall 5: Failing to Keep Detailed Records of Your Payments
Paperwork gets lost, systems get upgraded, and mistakes happen in large administrative databases. If you do not keep your own records, you have no way to prove your payment history if a discrepancy arises.
- Save confirmation emails: Keep a digital folder containing every receipt and notice from your servicer.
- Log annual changes: Write down your recertification dates and approved payment amounts each year.
- Audit your account periodically: Take ten minutes every few months to log in and verify your current balance.
Finding Confidence and Stability in Your Financial Journey
Navigating the world of federal student loans does not have to feel like walking through a dark maze. Armed with the right knowledge and a step-by-step approach, you can take control of your financial narrative. Every smart choice you make today builds a stronger foundation for your future. Remember that financial wellness is a marathon, not a sprint. You do not need to figure everything out by tomorrow morning. Take a deep breath, review your options, and start implementing these changes one small step at a time. Your future self will thank you for the effort you put in right now. Taking charge of my student debt completely shifted my mindset from feeling trapped to feeling fully empowered about my finances. You do not have to figure out everything today, but taking just one small step right now will completely change your peace of mind.


