
The Reality of Borrowing and Your Peace of Mind
I remember feeling like I had made a massive mistake the moment I walked out of the bank with my first loan. I was so caught up in getting the money I needed that I ignored the thick stack of papers they handed me, only to realize months later that I was paying much more than I planned. I felt foolish and trapped, but that experience taught me that I had to start reading the fine print if I ever wanted to get ahead. Have you ever felt that sinking feeling after signing a loan agreement? You thought you understood the monthly payment, but suddenly, the total cost seems much higher than you expected. This experience is common for many people. It feels like you are trapped in a maze of complex legal jargon and numbers that do not make sense. Your financial goals often take a backseat when unexpected charges begin to drain your monthly budget.
Why Common Borrowing Advice Often Fails
Many people struggle because they do not have the right tools to read a contract. They rely on simplified advertisements that hide the real numbers. Here is why the current way of borrowing causes so much trouble:
- Complex Language: Contracts use heavy legal terms designed to confuse the average borrower.
- Selective Disclosure: Advertisers highlight low interest rates but hide the extra processing costs.
- Pressure Tactics: Sales representatives push for a quick signature, leaving no time for a careful review.
- Lack of Transparency: Many borrowers do not know that fees can be negotiated or avoided entirely.
The Hidden Cost to Your Mental Well-being
Financial stress is more than just losing money; it impacts your daily happiness and your confidence. When you feel that you have been misled, it creates a lingering sense of doubt about your financial decisions.
- Constant Anxiety: You spend your time worrying about how to cover surprise expenses that keep popping up.
- Loss of Trust: You begin to fear banking institutions, which makes future financial planning feel scary.
- Sleep Deprivation: The stress of unexpected debt often keeps you up at night, affecting your productivity.
- Reduced Self-Worth: You might blame yourself for not being "smart enough" to spot the tricks, even when the system is rigged.
The hidden cost of these loans goes far beyond the interest rate. When you sign a contract without full clarity, you give away your power. You start to feel like you are working just to pay off fees you never truly agreed to in the first place. My biggest realization was that most lenders expect you to just accept their first offer without a word. I once wasted hundreds of dollars because I was too shy to ask about an origination fee, so now, I always come prepared with a simple question about whether a fee can be waived. It is a small change, but it saved me a lot of money once I stopped acting like a victim and started acting like a smart consumer. This cycle creates a burden that makes it hard to save for the future or handle emergencies. It is a weight that sits heavy on your shoulders, making you question every choice you make with your money. True financial health starts by realizing that you have the right to ask questions. You are the customer, and you deserve a clear picture of what you are paying for. Taking control of your contract is the first step toward getting your freedom back.
Step 1: Mastering the Anatomy of Your Loan Agreement
"Watch this short guide to see exactly what you need to look for when reading your loan papers. It covers the simple, hidden details that most people miss, which could save you a lot of stress in the long run."
The very first thing you must do is look for the Truth in Lending section. Every legitimate lender is required to provide a document that outlines the Annual Percentage Rate (APR). Do not confuse the interest rate with the APR. The interest rate is just the cost of borrowing the principal amount. The APR includes the interest rate plus other fees, giving you the true cost of the loan.
Start by grabbing a highlighter and marking every section that mentions a dollar amount. Look for words like "origination fee," "processing fee," or "underwriting cost." These are often charged upfront and deducted from the amount you actually receive. If you borrow ten thousand dollars but there is a five percent origination fee, you might only see nine thousand five hundred in your account. You are still paying interest on the full amount, which is a common trick. Ask yourself if the total cost is worth the purpose of the loan. If the fees are too high, they significantly reduce the value of the money you are borrowing. Take your time to calculate the total repayment amount manually. Do not just take the lender’s word for it. When you see the numbers on paper, the decision becomes much clearer.
Step 2: Investigating Hidden Recurring Charges
Many people focus only on the interest and ignore the servicing fees that appear later. Check your contract for clauses that mention "administrative charges" or "maintenance fees." These are often hidden in the fine print and can be charged monthly or annually. If you find these, ask if they can be waived. Sometimes, lenders will remove them if you simply express hesitation about signing the deal.
Also, look closely at the late payment fee structure. A single missed payment can trigger a massive surge in costs. Check if the lender charges a flat fee or a percentage of your total balance. You want a contract that is fair and predictable. If the penalty for being one day late is extremely high, consider that a red flag.
Consistency is key to a healthy financial life. If your loan has variable fees that change based on market conditions, you are taking on extra risk. Try to find a fixed-fee structure whenever possible. Knowing exactly what you will pay every single month allows you to budget effectively. It keeps your finances stable, even when life throws unexpected surprises your way.
Step 3: Assessing the Real Cost of Prepayment
Many borrowers ignore the prepayment penalty section, assuming they will pay the loan on time. However, paying off your loan early is usually the best way to save on interest. You need to check if your contract allows you to pay more than the minimum without a penalty. Some lenders penalize you for paying off the debt early because they lose out on the total interest they expected to earn.
If you find a prepayment penalty, treat it as a significant barrier. A good loan agreement should allow you to accelerate your payments whenever you have extra cash. Look for the phrase "no prepayment penalty" explicitly stated in the terms. If it is not there, ask for a written waiver or look for a different lender. This simple check can save you hundreds or even thousands of dollars over the life of your loan.
Your goal is to be debt-free as fast as possible. Never lock yourself into a contract that forces you to stay in debt for a longer time than necessary. By understanding these three steps, you transform from a passive borrower into an informed consumer. You protect your bank account and gain the confidence to manage your future wealth. Keep your records, keep your cool, and always read the fine print before putting pen to paper.
Step 4: The Art of Negotiating Your Loan Terms
Many people assume a loan contract is a "take it or leave it" document. This is a massive myth. You have more power than you realize when you sit down at the table. If you spot a high fee, ask the lender to remove it or reduce it.
Focus on the origination fee first. If your credit score is strong, use it as leverage. Say, "I have other offers with lower fees, and I would prefer to work with you if you can waive this charge." Lenders want your business. They will often drop certain fees just to keep you from walking away.
Always get any verbal agreement in writing. Never sign a document that has empty spaces or blanks. If they say they are waiving a fee, make sure it is clearly crossed out or listed as zero in the final contract. Written proof is your best friend.
Think of it like shopping for a car. You wouldn't pay the sticker price without checking for discounts. A loan is a financial product, and you are the customer. Be polite but firm in your requests. You might be surprised at how often they agree to your terms.
Step 5: Building a Buffer for Unforeseen Costs
Even with a perfect contract, it is smart to plan for the unexpected. Sometimes, a bank might add a fee for a paper statement or a special payment processing method. Build a small financial cushion into your monthly budget to handle these minor costs.
Set aside a portion of your monthly income specifically for your loan payments. If you account for extra fees in your math, you will never feel caught off guard. This approach creates a sense of calm around your debt. It prevents small charges from becoming big disasters.
Use digital tools to track your payments. Set up alerts on your phone for a few days before your due date. This helps you avoid late fees, which are the most common source of extra cost. Automation is a powerful tool for maintaining a clean financial record.
If you ever feel overwhelmed, talk to a financial counselor. They can help you organize your debt strategy. Keeping your finances simple is the best way to maintain peace of mind. Remember, your goal is to pay off the debt, not to stay in a long-term relationship with the lender.
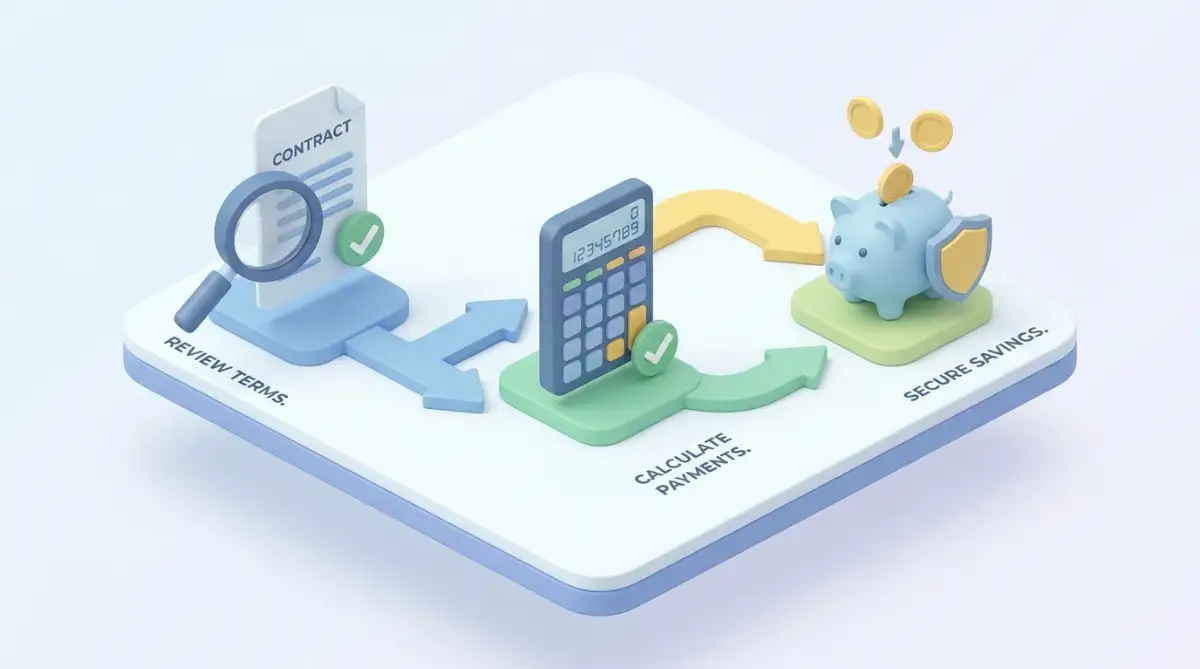
Mistakes That Can Cost You Your Future
Trying to manage loans is tricky. People often rush through the process because they just want the money. Here are five big mistakes that can lead to long-term financial pain.
- Ignoring the Fine Print: People often skip the long pages of legal text. This is where the sneaky fees hide. Read every single word before you sign.
- Borrowing More Than Needed: Just because a bank approves you for a high amount does not mean you should take it. Only borrow what is required to avoid extra interest and fees.
- Missing Payment Deadlines: A single late payment can wreck your credit score. This makes all your future loans much more expensive.
- Accepting Variable Interest Rates: These rates can skyrocket without warning. A fixed-rate loan is almost always safer for your budget.
- Failing to Compare Offers: Never take the first loan you are offered. Compare at least three different lenders to ensure you are getting the best market deal.
Avoiding these pitfalls will save you a lot of money. When you avoid these errors, you keep your credit score healthy. A healthy score is like a golden ticket for your future. It opens doors for lower interest rates on houses, cars, and future business needs.
Take Control of Your Financial Path
I promise that once you stop being intimidated by these numbers, you will feel a weight lift off your shoulders. You have worked too hard to let hidden fees eat away at your future, so take that first step today by reviewing one contract you have. You are fully capable of managing your own money, and taking action right now is the best way to start your journey toward a debt-free life. You are now equipped with the knowledge to handle your loan agreements. Do not let complex numbers intimidate you. You have the right to ask questions and demand transparency. Your money belongs to you, and protecting it is your responsibility.
Take this step today. Review your existing contracts and look for any areas where you can save. If you are planning to get a new loan, use these tips to stay safe. Knowledge is the ultimate tool for financial freedom. Start small, stay organized, and always keep your long-term goals in sight. You are doing a great job by taking these steps. You have the power to master your finances and build a secure, debt-free future. Keep moving forward with confidence.


